
"Safety and certainty in oil lie in variety and variety alone" - Winston Churchill
CAPITALS.
War reached capital cities this week.
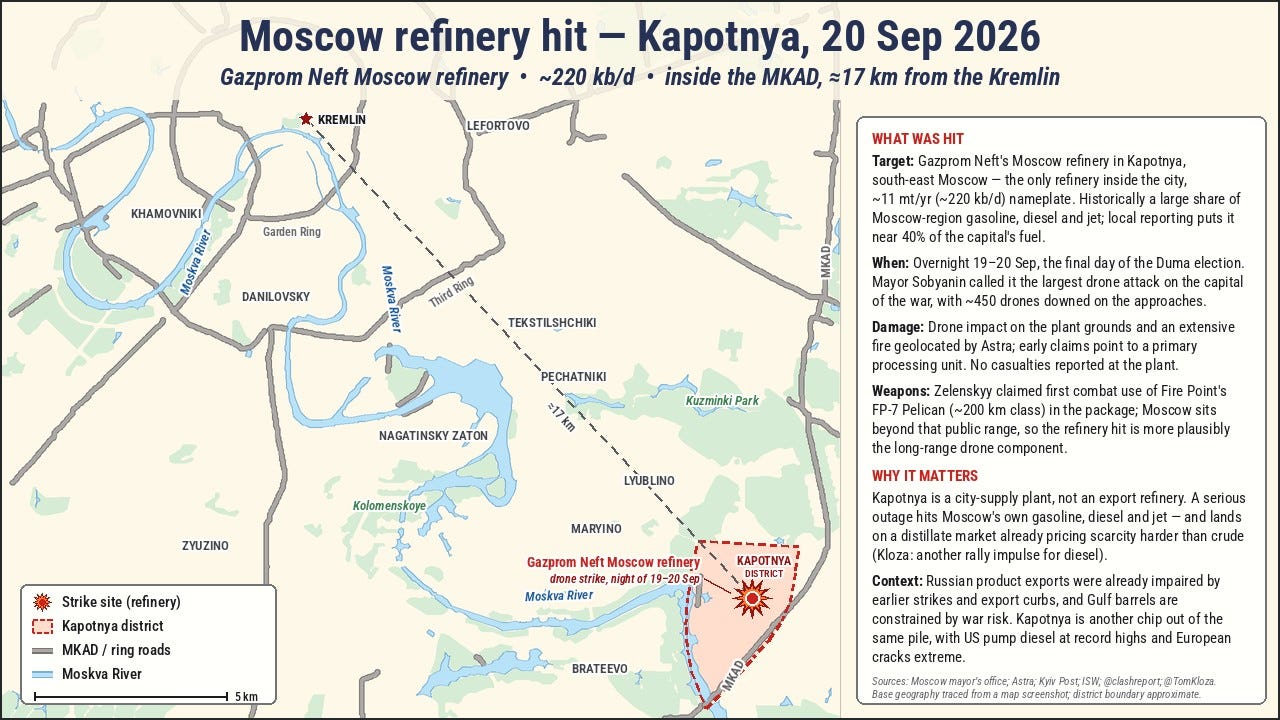
The Houthis hit Riyadh for the first time, and overnight into Sunday Ukrainian drones hit the Gazprom Neft refinery at Kapotnya - inside Moscow’s city limits.
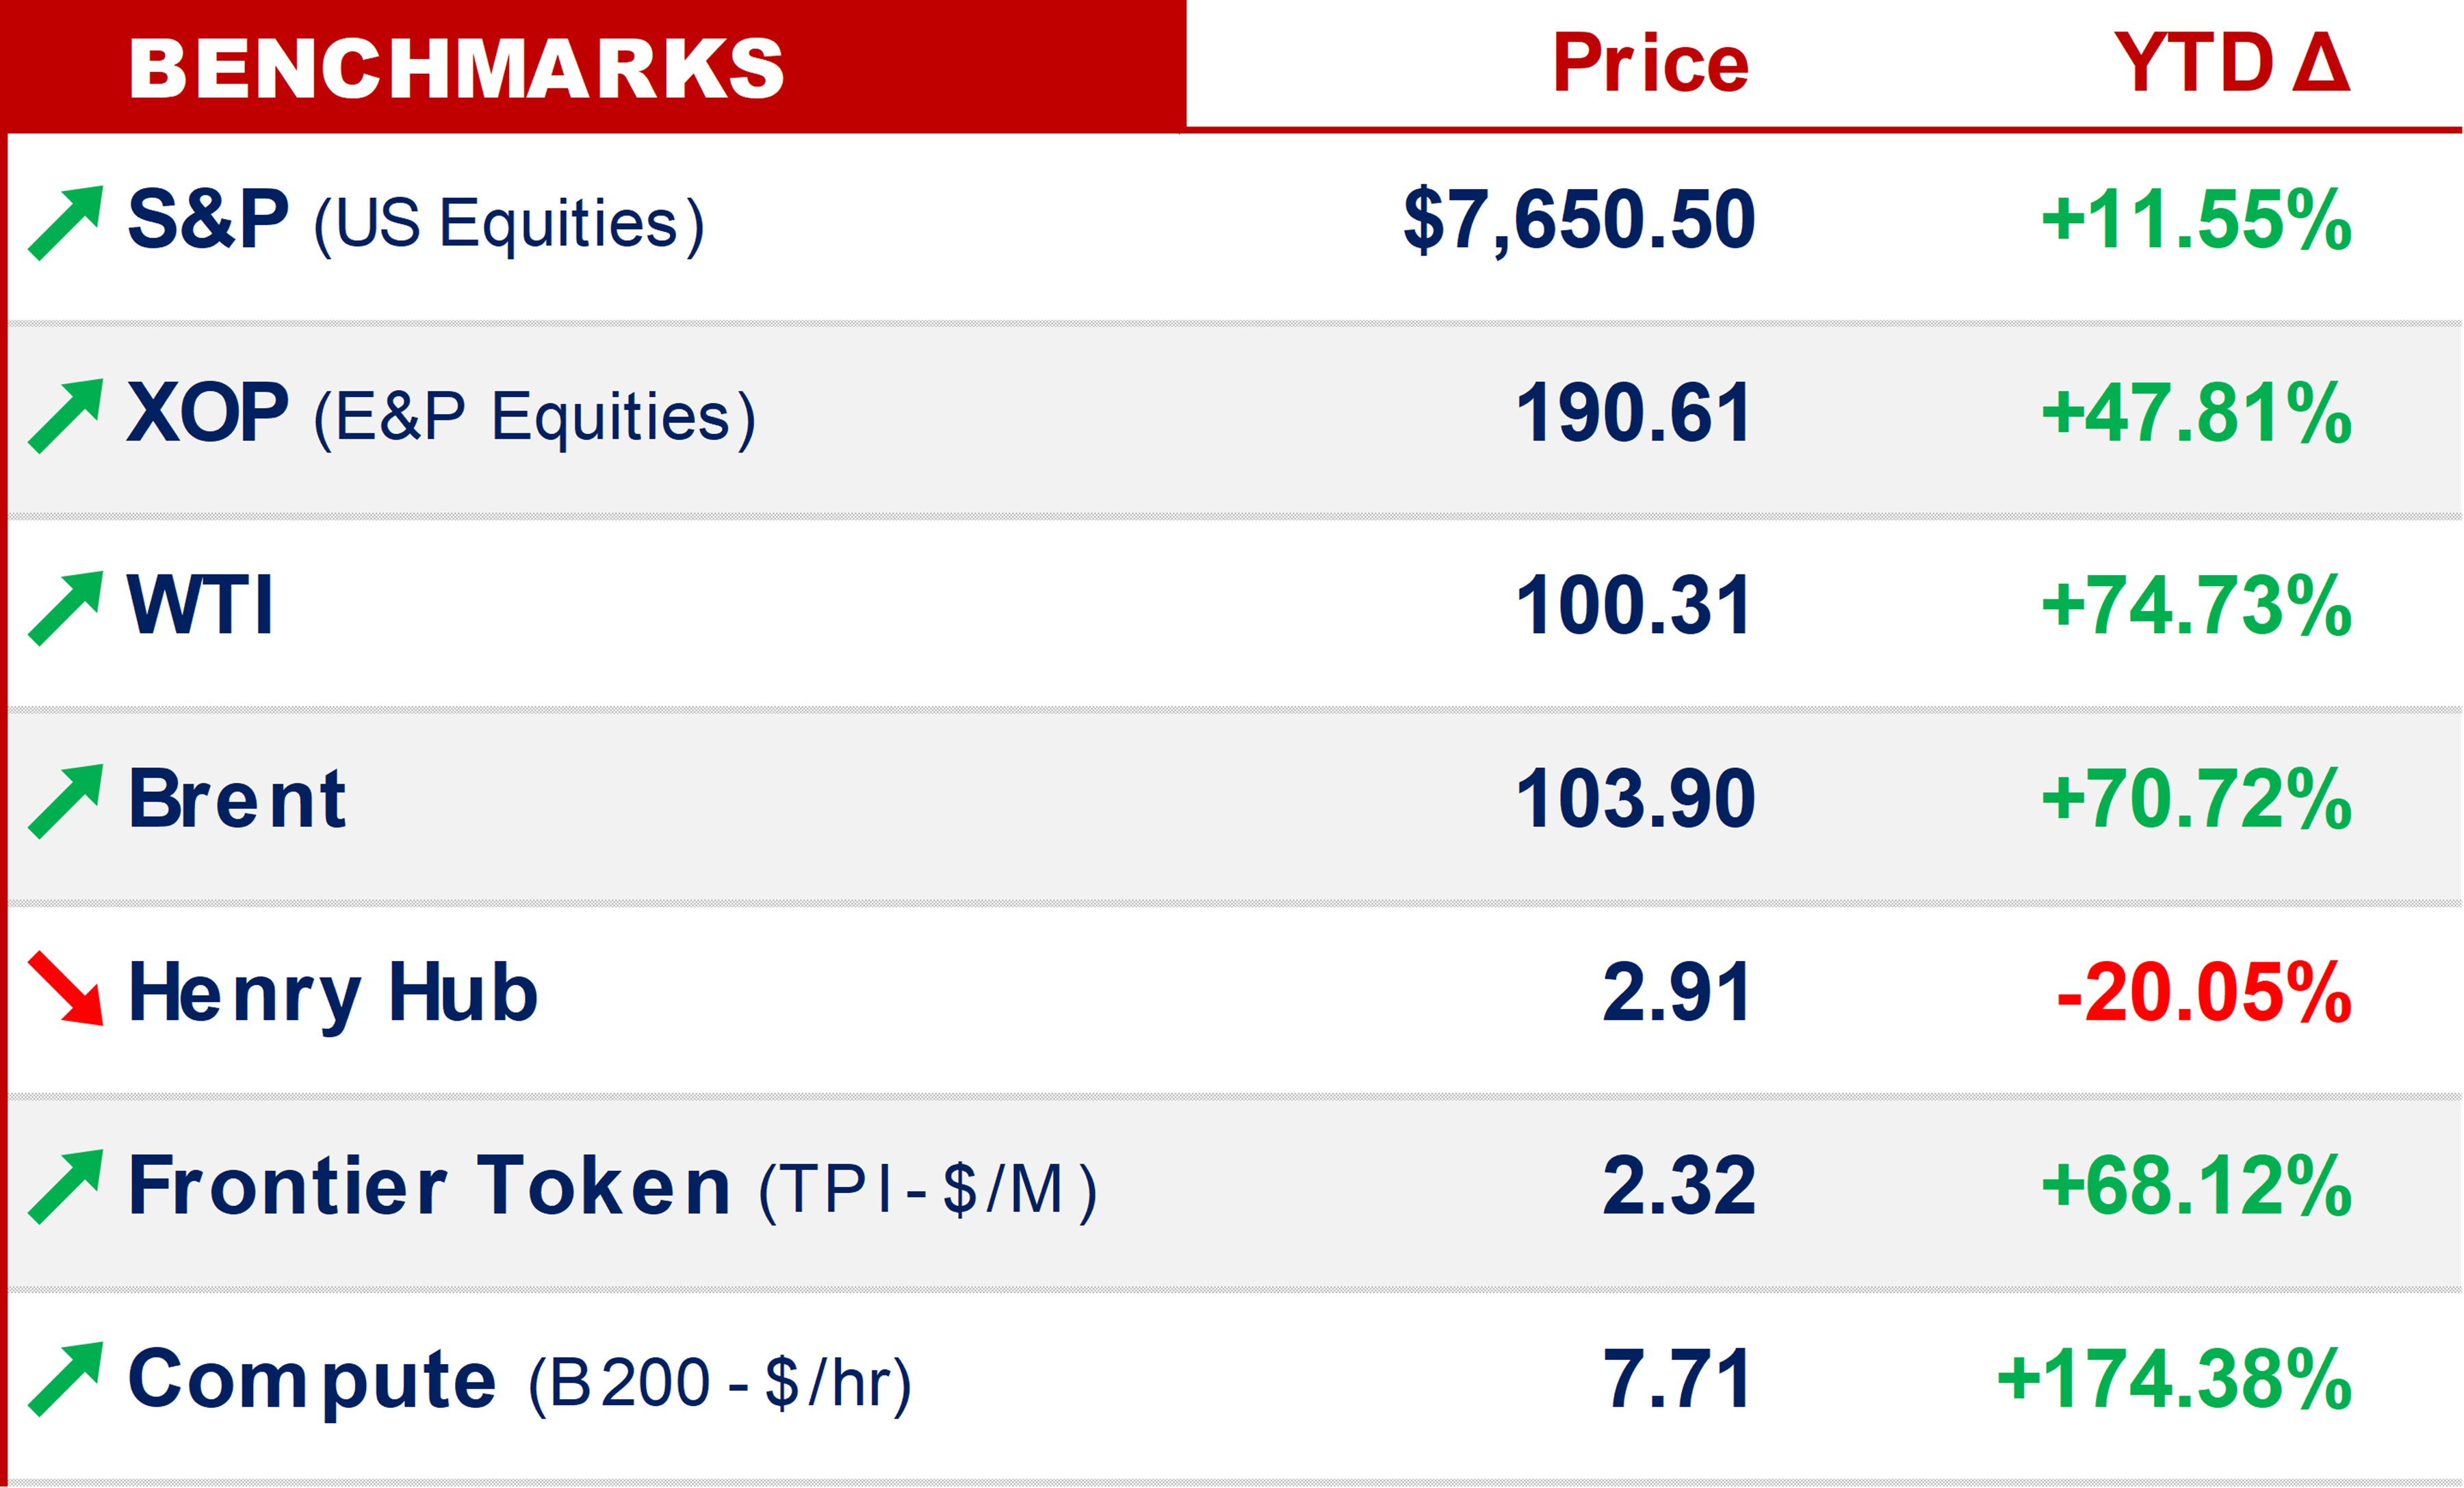
Meanwhile, Dated Brent printed around $132 & every North Sea grade cleared $150 on a dated-plus-differential basis.
Starting w/ Riyadh…
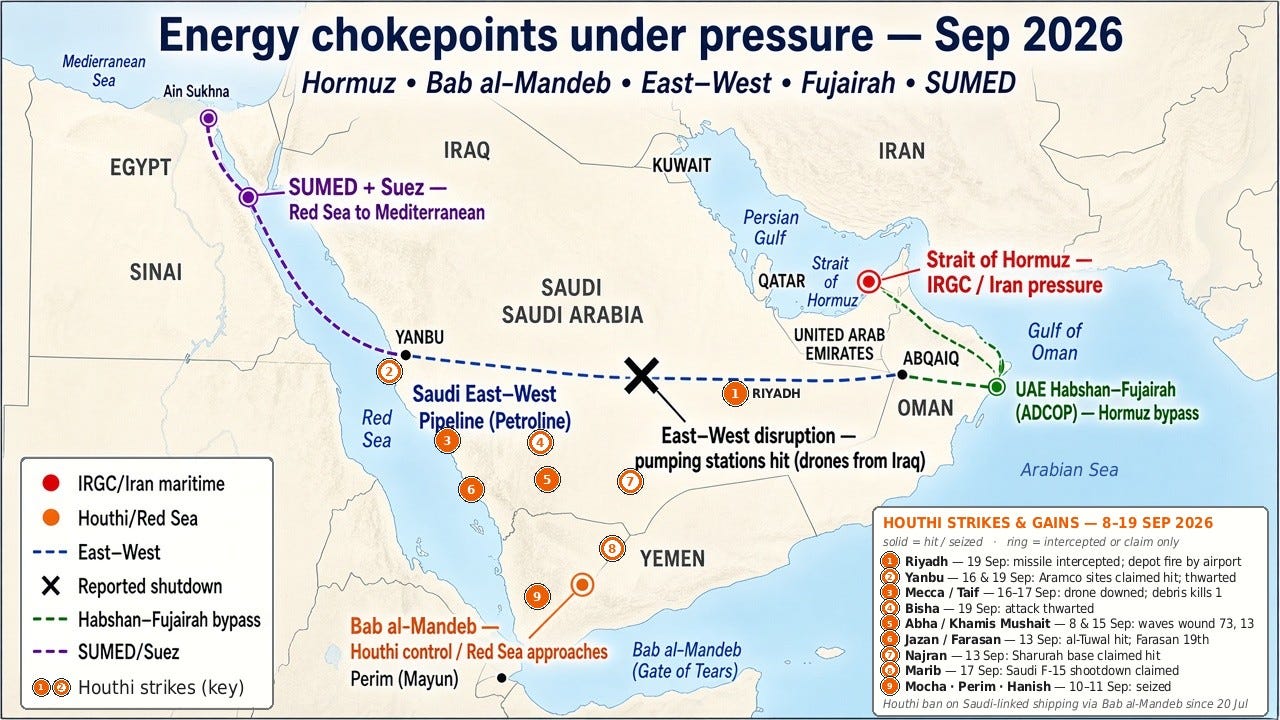
Per the ISW, the strike is part of a Houthi campaign to impose maximum political & economic cost on Saudi Arabia until Riyadh yields.
Inside Yemen, pressure around Taiz continues (Saudi media claimed a government-aligned seizure of Jabal Naman), which ISW reads as serving near-term economic aims & the longer goal of controlling Yemen.
Last week Trump declined Saudi requests to strike the Houthis.
This week he reportedly reviewed strike options at Camp David - then returned to Washington a day early.
The State Department issued a Middle East security alert citing the potential for unforeseen escalation.
ISW sees multiple signs that fighting between the US & Iran and its partners may expand imminently.
On the other side, Tehran’s answer came from its highest operational headquarters:
It claims intelligence that the US intends to resume strikes on Iran & has put forces on high alert.
If struck, Iran would attack US bases & interests - and show no “restraint or decency” toward regional countries that support the strikes.
The ISW reads that last line as aimed at the neighbours - pressure on the Gulf to talk Trump out of it.
Stack it on last week’s tape - Bab al-Mandeb, Hormuz, the East-West shutdown - and this is no longer Houthi harassment at the periphery.
Capital-city signalling, US decision time & Iranian escalation doctrine…
… all inside the same 48hr window -
MOSCOW.
Kapotnya is ~220 kb/d nameplate & has historically supplied a large share of the Moscow region’s gasoline, diesel & jet (not a marginal topping plant).
Russian authorities described one of the largest drone waves of the year against the Moscow region, w/ fire & damage reported at the plant (early claims point to a primary processing unit).
Tom Kloza’s read (we agree): if Kapotnya is seriously impaired, Muscovites lose a huge slice of local product & diesel gets another rally impulse.
On election weekend, no less -
PRODUCTS.
Products are (still) the problem:
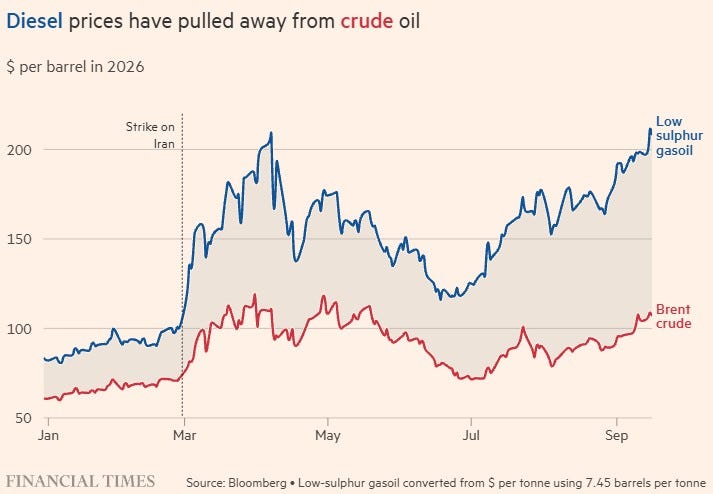
GasBuddy has the top 10% of US stations above $7/gal on diesel, the bottom 10% around $5.83 & the median near $6.39, w/ further gains expected.
The FT’s chart shows diesel pulling away from crude - the signature of a refining & availability problem, not a simple crude shortage.
Russian product exports were already impaired by earlier strikes & export curbs.
Gulf barrels are constrained by war risk.
Kapotnya is another chip out of the same pile.
And the physical barrels agree:
@Big_Orrin has every North Sea grade at $16-$24 over Dated.
June Goh (Sparta) had Johan Sverdrup at about Dated+$22 & Forties at about Dated+$16 midweek, w/ medium sours holding a clear premium to lights & NW European margins still strong enough to keep secondary units full.
While there’s scarcity pricing in the physical complex…
… the market is saying that Northern Europe wants the barrels & is paying for them.
Inventory headlines matter less than what can clear the water & the rack this week.
And the mid-terms are now 6wks out -
OTHER.
Noam Raydan’s Seatrade conversation on Iran’s attack pattern on shipping & what operators should expect next
That’s it for this week -