
“The past is never dead. It’s not even past” - William Faulkner, Requiem for a Nun
Editor’s note: Anthropic is scheduled to IPO this week; having previously shared a primer over the summer on Frontier Labs, I’ve leveraged that work - as well as the wonderful public work of Jared Kubin, Brett Caughran, and Shanu Mathew - to build a model & primer for Anthropic’s IPO.
If that’s of interest to you, feel free to read / download the materials here (and, if you’d like my qualitative opinion, feel free to email me) -
If you find this newsletter helpful, forward it to a friend or colleague - on to oil -
A GLUT.
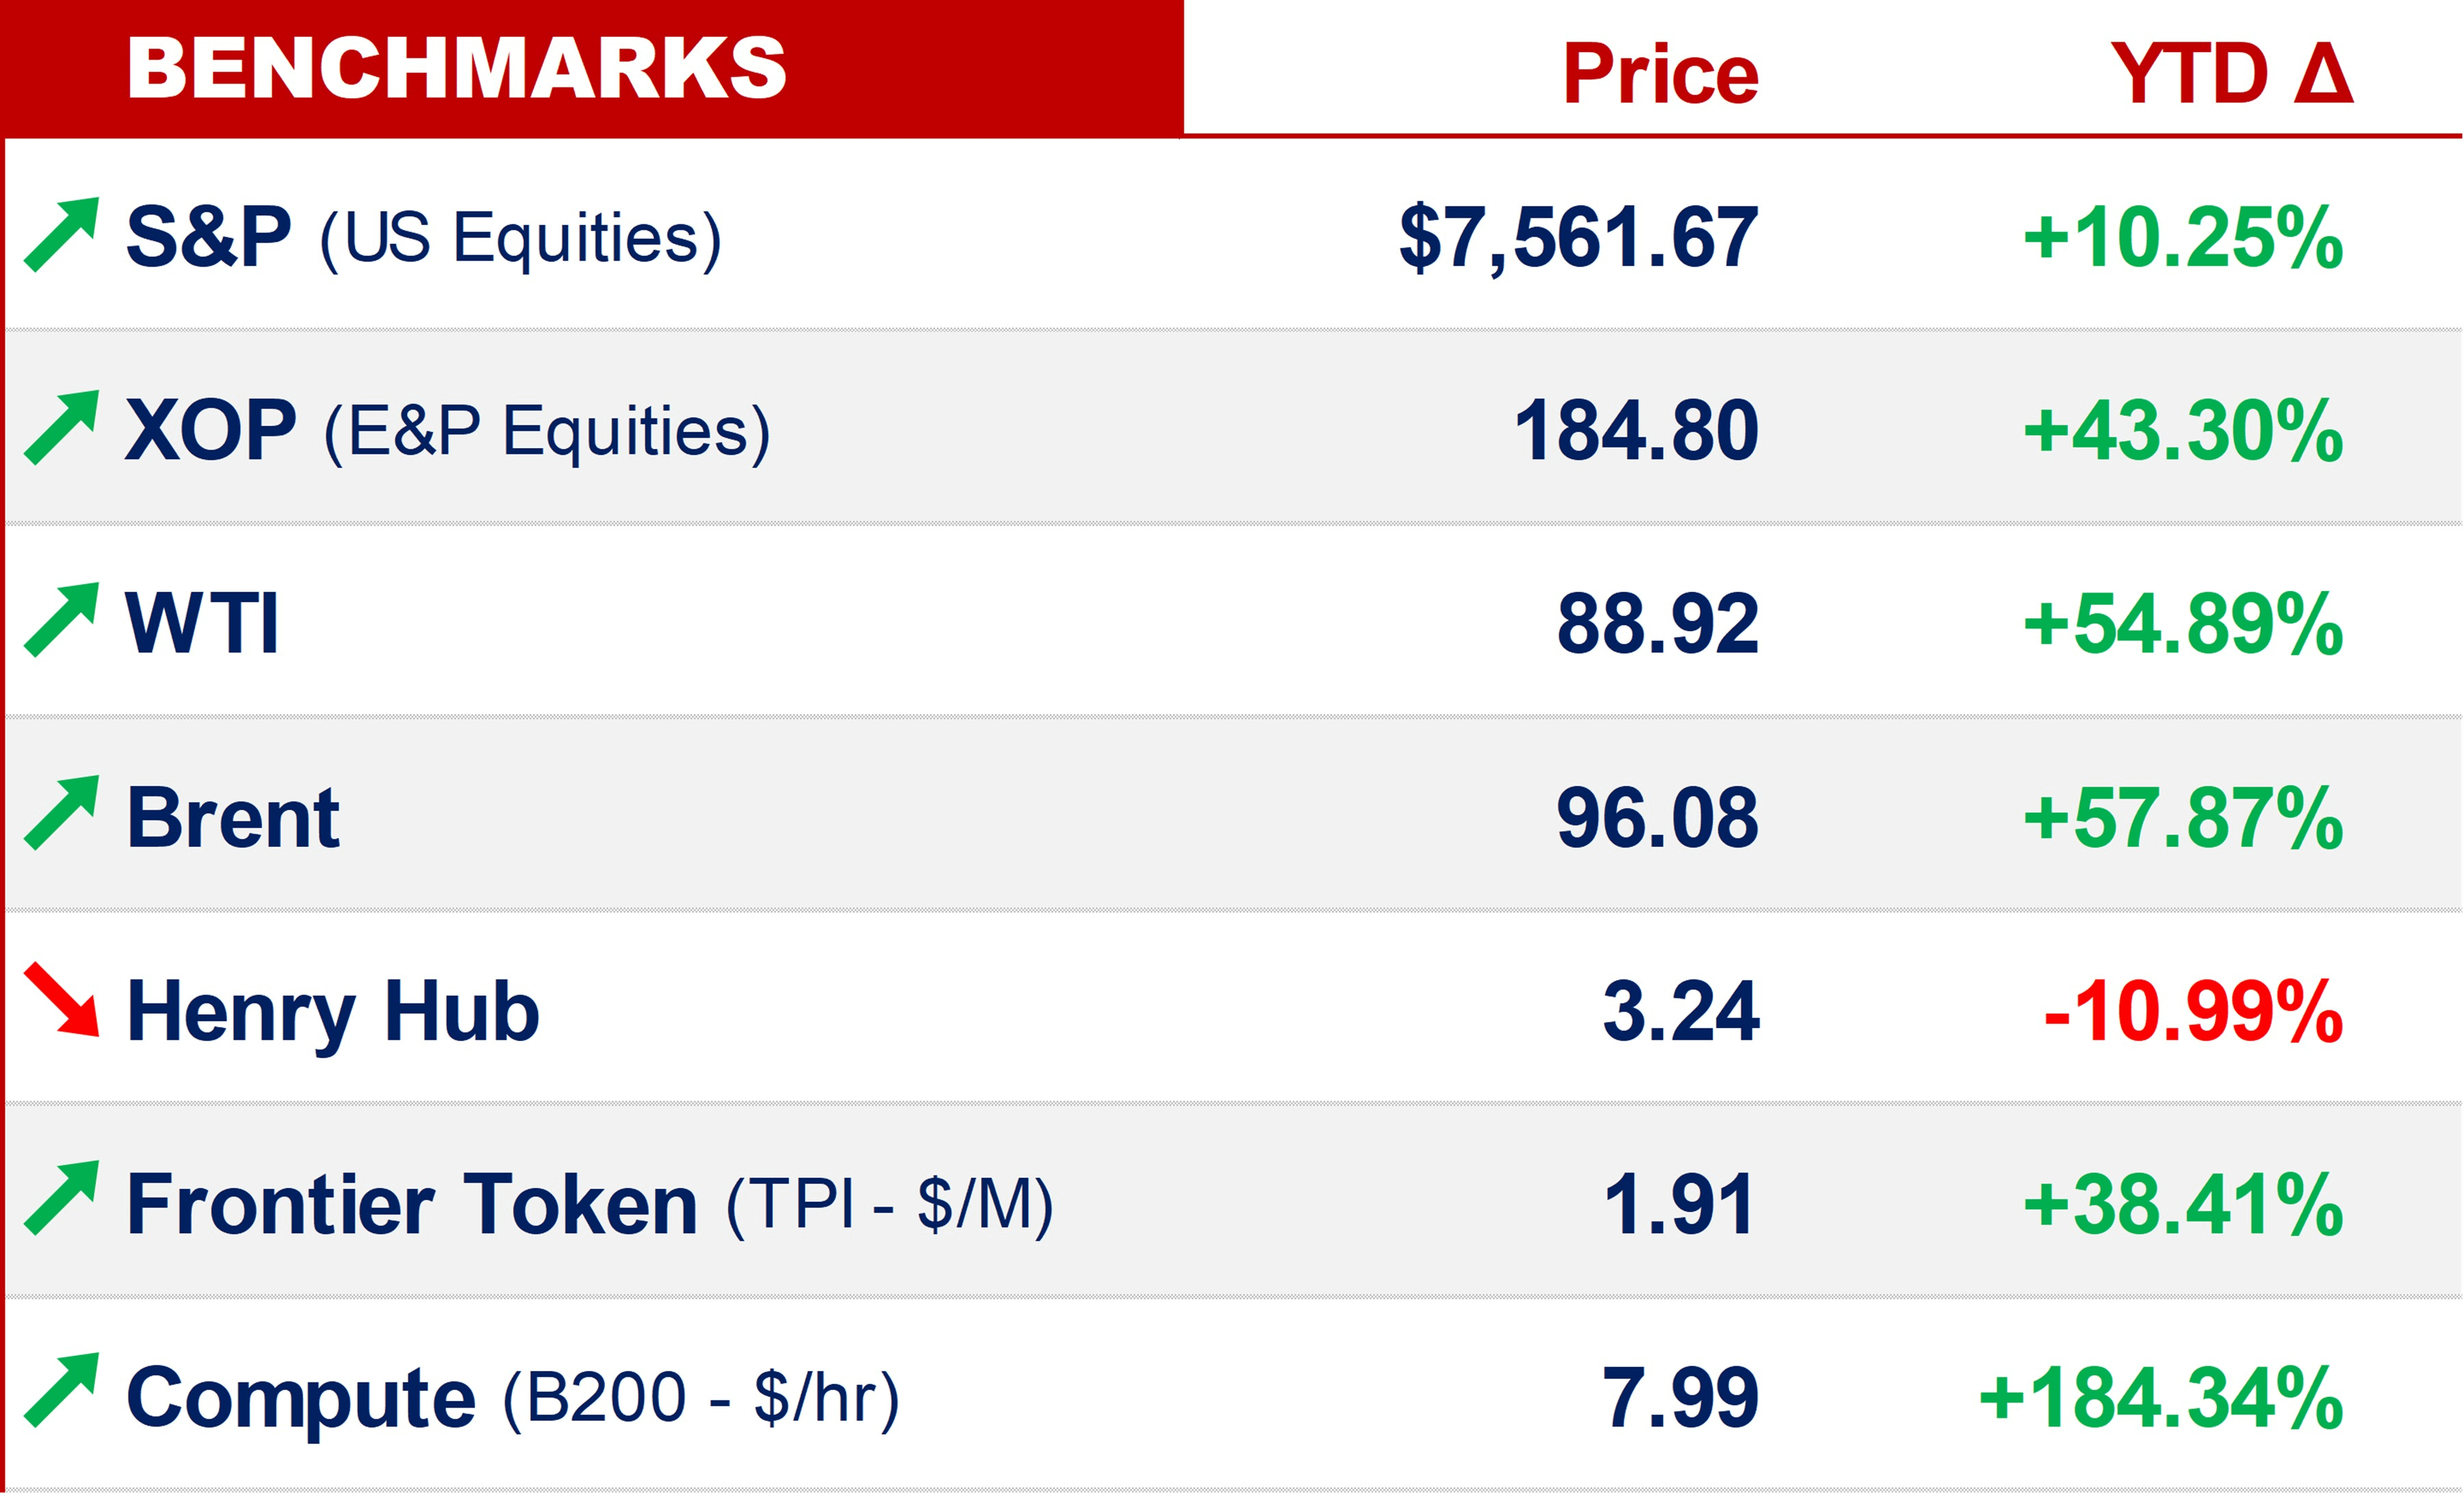
Crude fell for a second straight week, though by a lot less than last week’s ~16%.
This time the reason was barrels, not diplomacy:
Jan Brent settled at $95.84 on Friday, down from $98.32 a week earlier - about -2.5%
The low came early. Brent fell 5.85% on Monday after Trump said he’d hold off on more strikes on Iran - while keeping the blockade - & on Tuesday it touched $89.65, its first trade below $90 since Aug 31st (Gulf News)
Then it bounced ~3% on Nov 12th, when the Houthis went after Saudi infrastructure (more below)
The IEA says supply overtook demand in October for the first time since the Iran war began, by nearly 2MM b/d (@Rory_Johnston, @JavierBlas).
The catch: much of that crude is still at sea.
Not in tanks…
The barrels are coming from the Gulf.
Iraq’s October output hit a seven-year high of ~4.6MM b/d, & Saudi output surged (@JavierBlas).
As much as this is driven by geopolitical instability, there exists a feeling that the UAE’s exit from OPEC in May - and the damage that can do to cartel cooperation - is pain in the price of crude, being noticeably felt today -
THE PENINSULA.
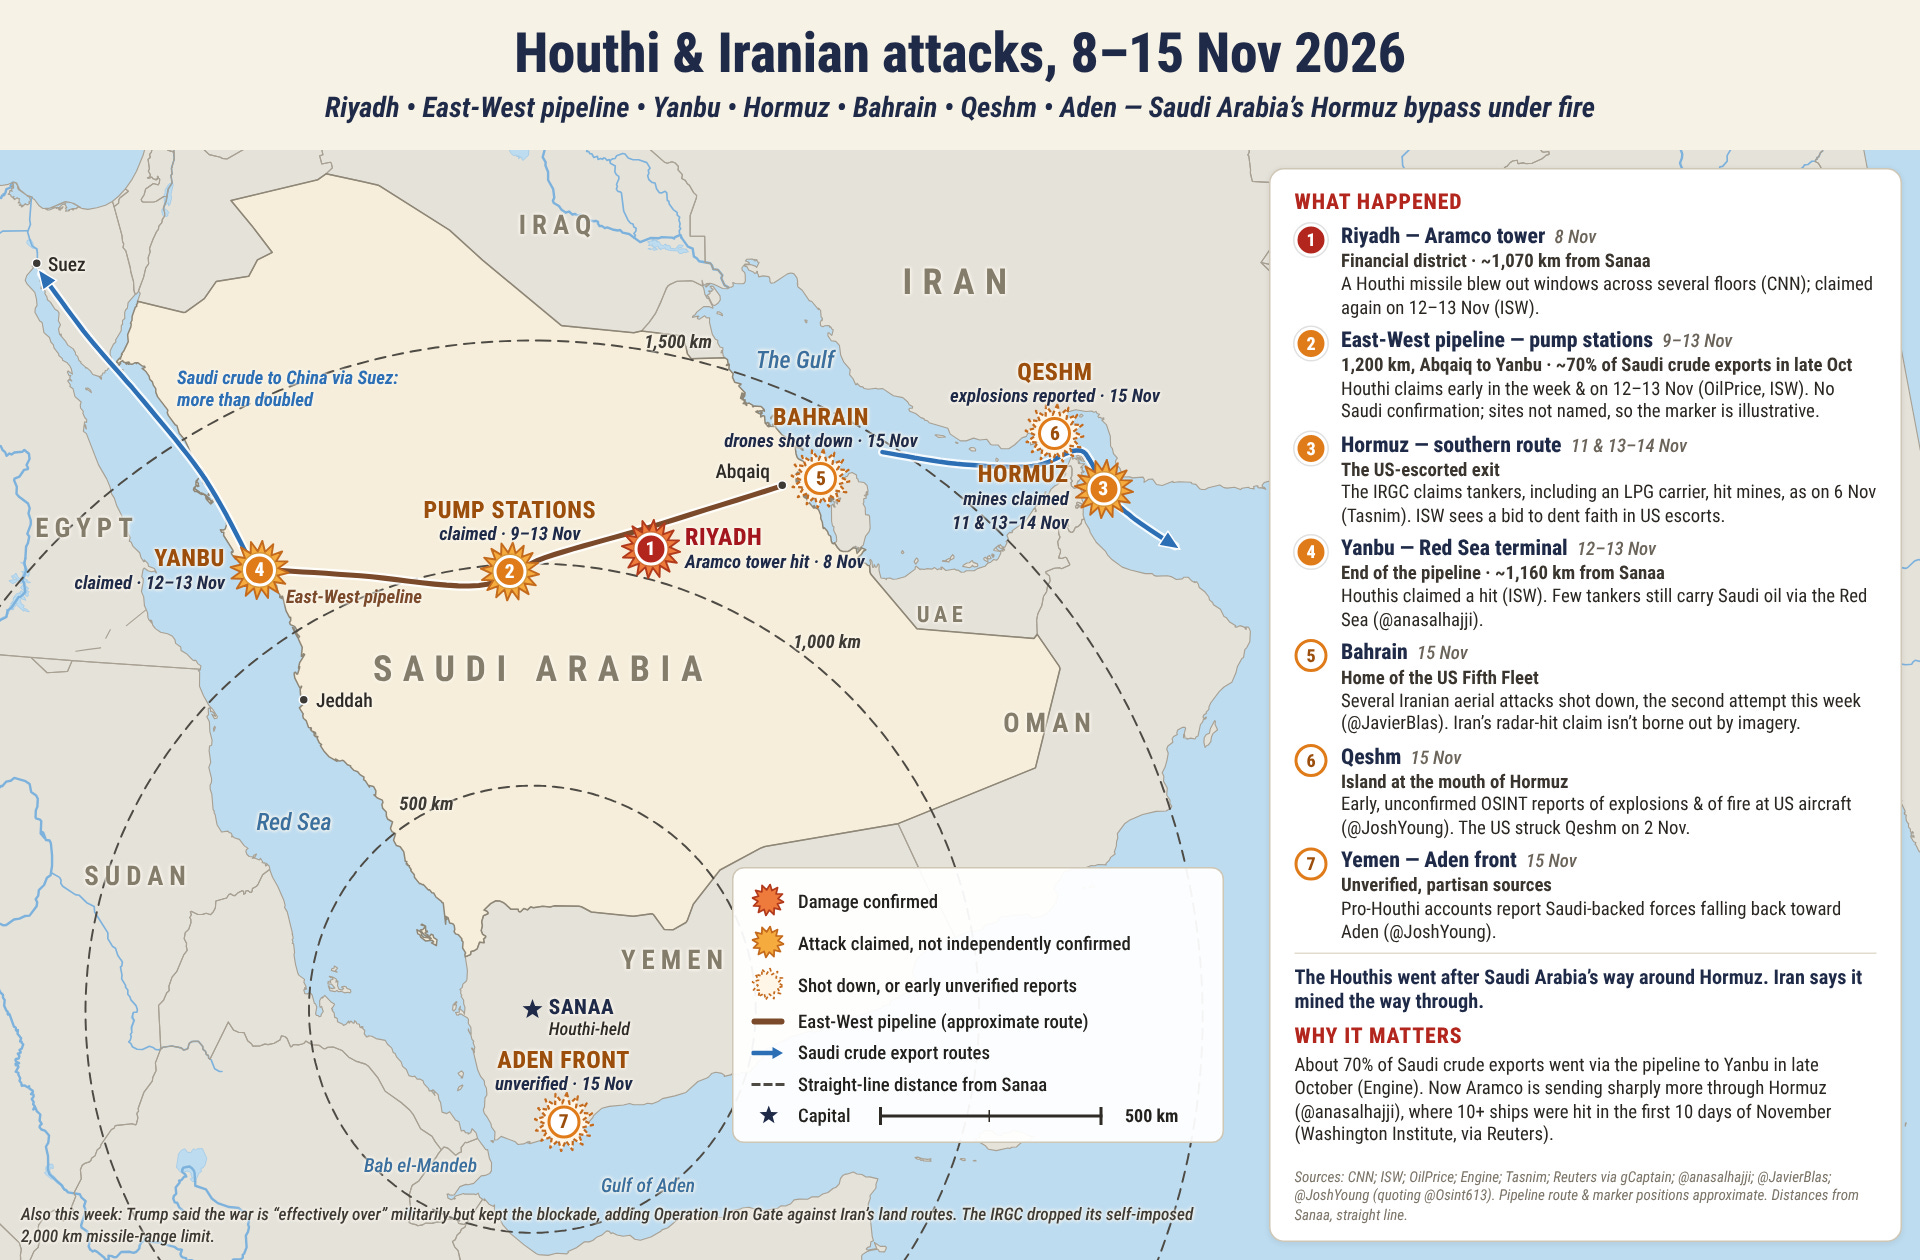
Saudi Arabia built the East-West pipeline so it would never have to rely on Hormuz.
The Houthis have noticed…
Early in the week the Houthis claimed more hits on the pipeline’s pump stations, & Brent fell anyway on Monday (OilPrice).
By Thursday the market was listening: crude jumped ~3% as they claimed hits on a pump station, on Yanbu & on an Aramco building in Riyadh over Nov 12th-13th (ISW).
The 1,200km pipeline carries crude from the eastern fields to Yanbu on the Red Sea - the route for ~70% of Saudi crude exports as of late October (Engine)
It was down for two weeks in September after drones hit its pump stations, & the Houthis claimed it again in late October (OilPrice)
So, Riyadh is going the other way.
Aramco has sharply increased exports through Hormuz, & few tankers still carry Saudi oil via the Red Sea (@anasalhajji).
What does still load at Yanbu heads north: Saudi crude to China via Suez has more than doubled.
Which leaves the way through - where Iran says it’s laying mines…
In late October, CENTCOM said Hormuz’s shipping lanes were clear of mines (Shafaq). Iran has been claiming mine hits on the escorted route ever since -
Mines: the IRGC claimed tankers hit mines on Nov 6th (Tasnim) & Nov 11th (Tasnim), & again on Nov 13th-14th - this time including an LPG carrier. ISW reads the claims as a bid to undermine confidence in US escorts
Attacks: UKMTO logged 7x tanker attacks in the week to Nov 11th. At least 10x ships were hit in the first 10 days of November, after 37x in October - the most in any month of the war, per the Washington Institute (Reuters, via gCaptain)
Flows: overall, TankerTrackers sees fewer barrels leaving Hormuz, & a Teekay executive says a resolution is “a ways away”
Washington: on Monday, Trump said that militarily the war is “effectively over” - but the blockade stays, joined by a new Operation Iron Gate aimed at Iran’s land routes (Israel Hayom). By the end of the week he was saying the US “doesn’t need” a deal. Netanyahu says it’s time to remove the Iran threat “once and for all”
Tehran: the IRGC formally dropped its self-imposed 2,000km missile-range limit (Al Jazeera), & Iran told the IAEA that monitoring can’t continue while it’s under threat. US officials told the WSJ that analysts put Iran’s missile stock at 1,500-2,500 - a low-confidence estimate (@sentdefender)
Bahrain: Iran claimed it hit a US radar there, but satellite imagery shows it undamaged. Sirens sounded twice overnight into Sunday, & Bahrain says its air defenses shot down several Iranian aerial attacks on Sunday - the second Iranian drone attempt on it this week (@JavierBlas)
*TEN REFINERIES.
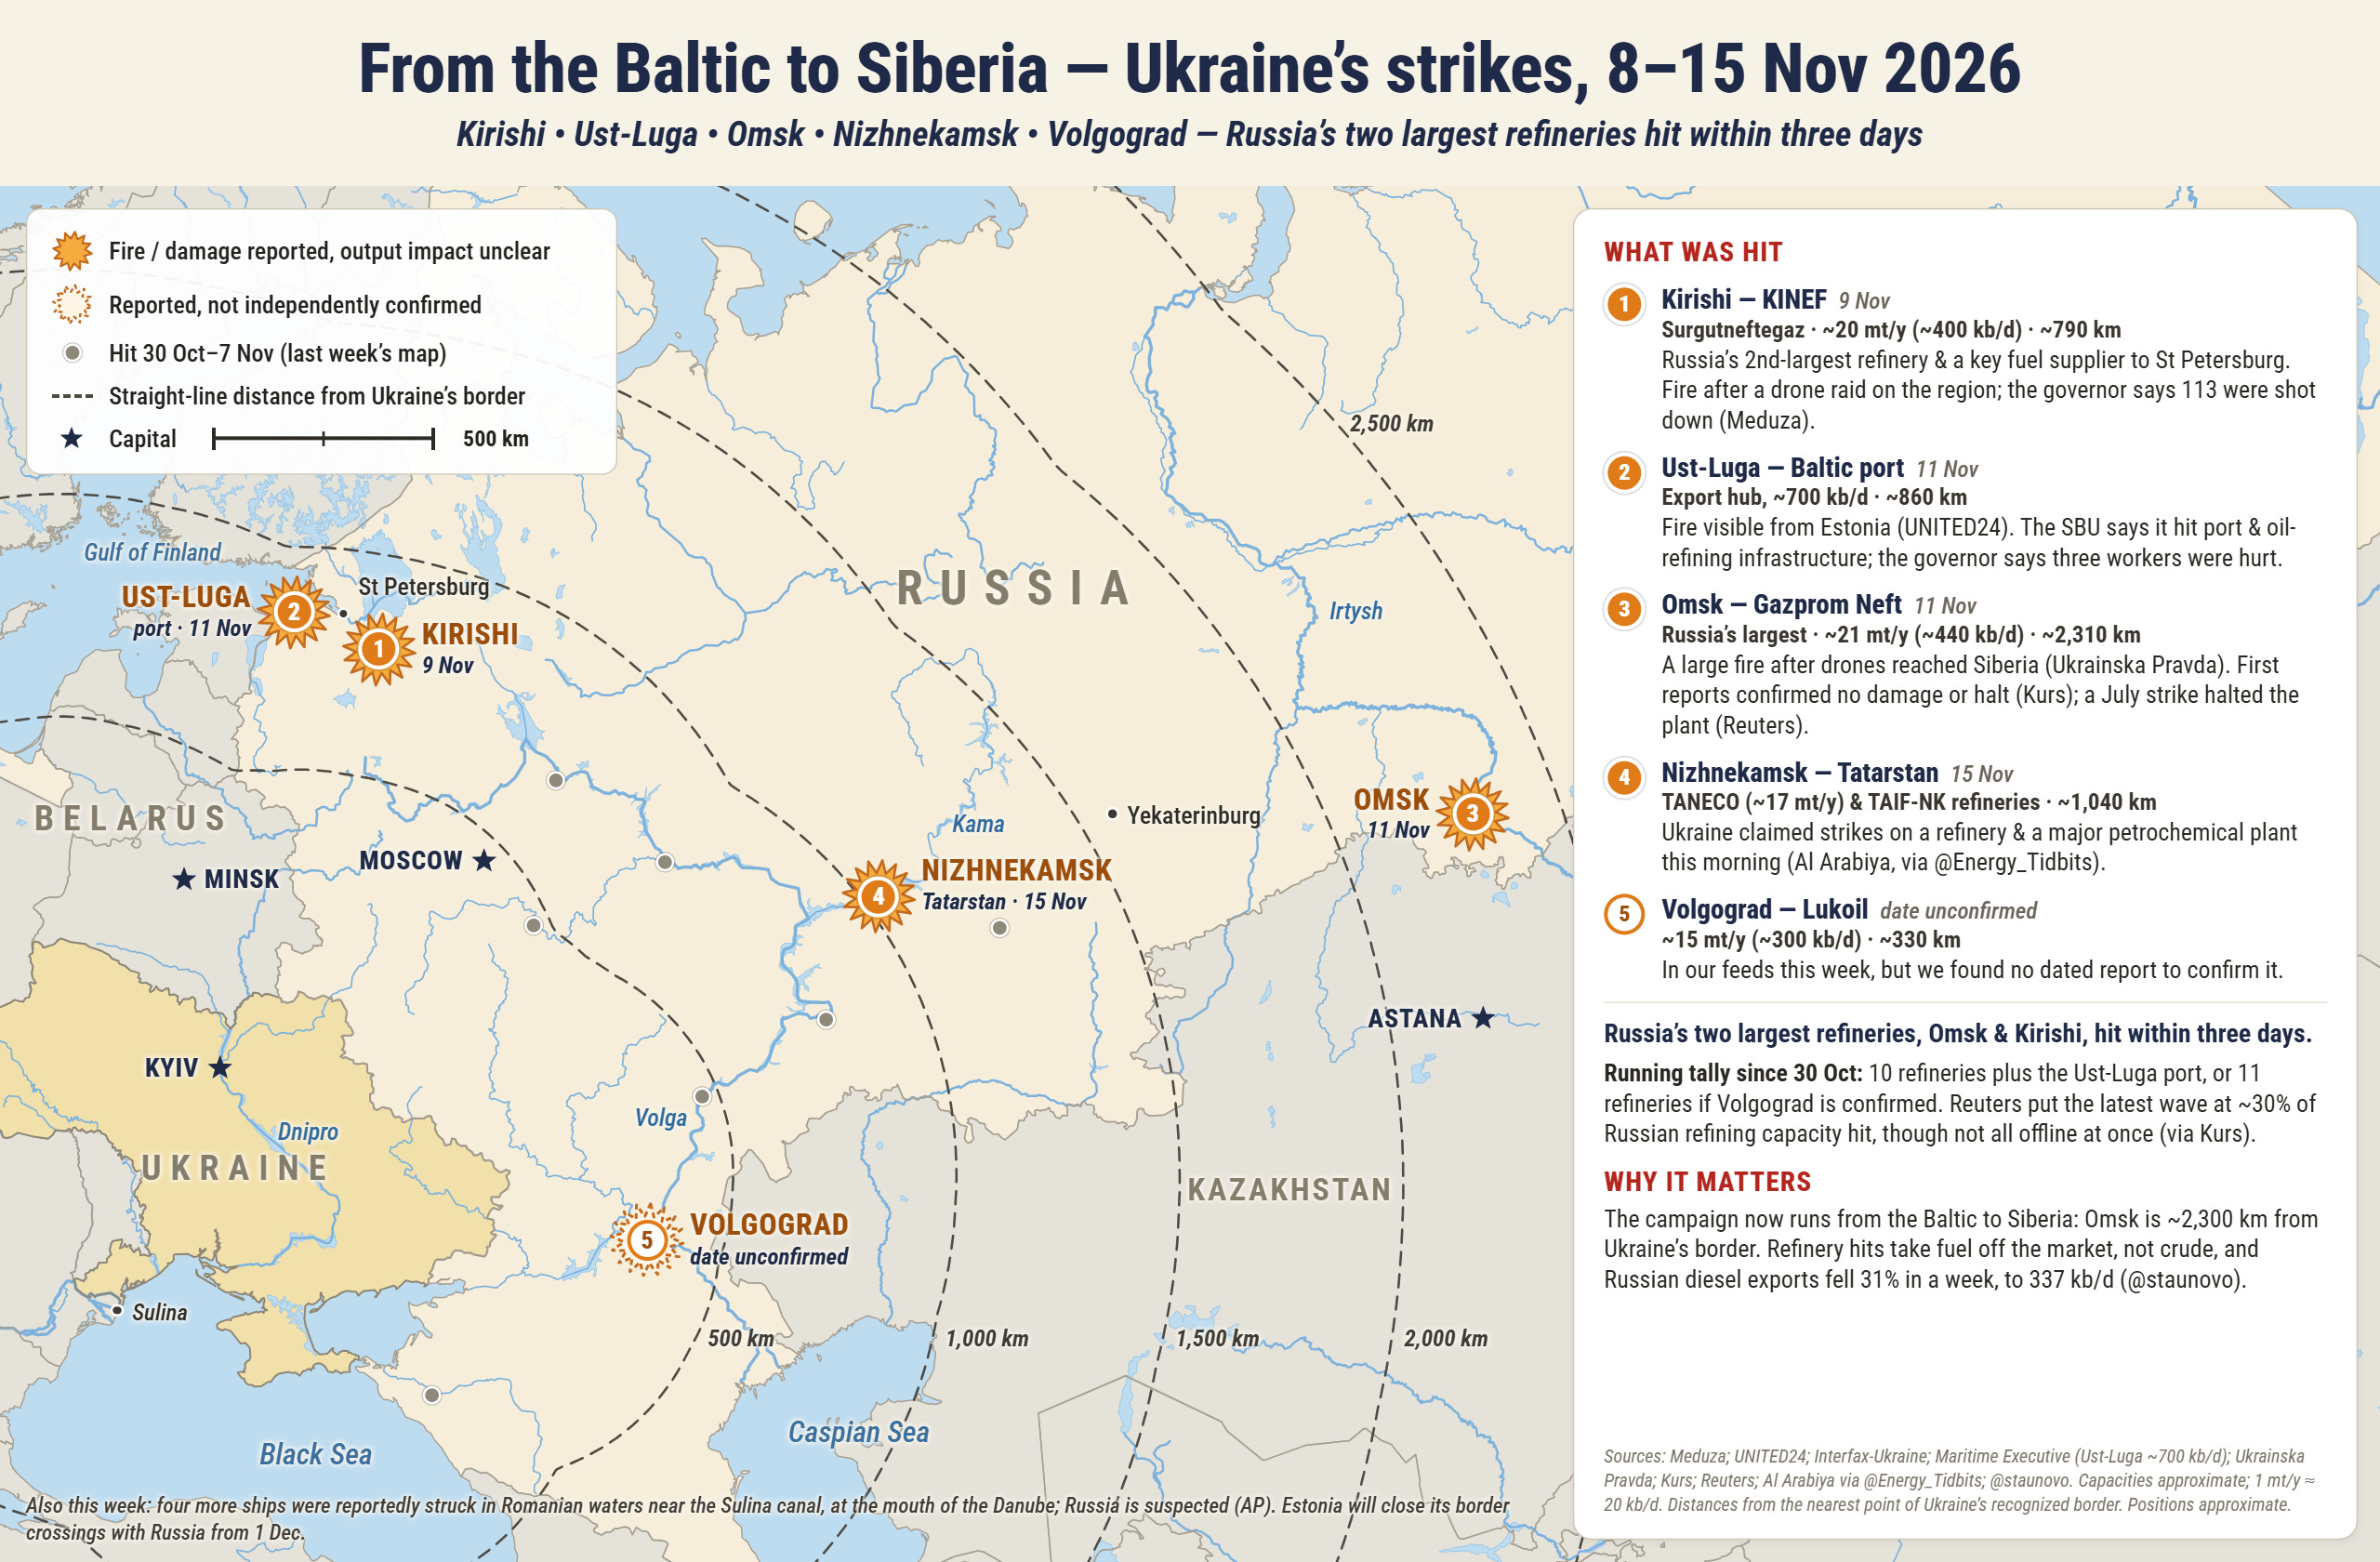
Last week it was 7 refineries in nine days. By Sunday it was at least ten in November alone:
Nov 9th - Kirishi (KINEF, Russia’s 2nd-largest refinery & a key fuel supplier to St Petersburg). A fire after a drone raid on the Leningrad region - the governor says 113 were shot down; a woman died from falling debris in Vsevolozhsk (Meduza)
Nov 11th - Ust-Luga (Baltic export hub, ~700kb/d). The SBU says it hit port & oil-refining infrastructure; the governor says three workers were hurt (Interfax-Ukraine)
Nov 11th - Omsk (Gazprom Neft - Russia’s largest refinery, ~2,500km from Ukraine’s border). A large fire after drones reached Siberia again (Ukrainska Pravda)
Volgograd (Lukoil), hit again this week
Sunday - Nizhnekamsk (Tatarstan). Ukraine has now claimed this morning’s strikes on a refinery & a major petrochemical plant (@Energy_Tidbits, via Al Arabiya)
Last week we said the refinery war takes product off the market, not crude.
Here’s the product - Russian diesel exports fell 31% in a week, to 340kb/d -
RATES.
Crude fell for a second week. The bond market didn’t get the memo -
The US 10-year closed at 5.15%, up 29bps on the week - its biggest weekly rise in 19 months
The trigger was Tuesday’s hot CPI. That morning Fed Governor Waller said he’d back a December hike - & that half-point move should be considered if core came in at 0.3% or more. It came in at 0.3%: the 2-year jumped ~18bps & the 10-year briefly topped 5% (Babypips)
After the print, CME FedWatch had a December hike fully priced - 91% for a quarter-point, 9% for a half (CNN, via KEYT); in Europe, the ECB’s Nagel called more rises “highly probable”
The oil market is pricing the end of the war. The bond market is still pricing what the war did to inflation -
OTHER NEWS.
Gas: US natgas rose 8% on the week, to $3.23
Gasoline: US pump prices fell almost 20c in a week, to $3.87 a gallon (@TomKloza)
Jones Act: the US issued a new three-month waiver, though the American Maritime Partnership had urged Trump to let it lapse on Nov 15th (gCaptain)
Guyana: Exxon gave the go-ahead to Longtail, a $12.5BN project that will be Guyana’s first dedicated gas development (OilNOW has the background)
Peoria: the FBI is investigating an explosive device found at the BioUrja ethanol plant in Peoria, Illinois (@sentdefender)
That’s it for today - see you next week -