
“…large supplies of gasoline which is, in the battle of tomorrow, as necessary as blood” - Georges Clemenceau
Editor’s note: skipping next week on account of travel; back on October 11th -
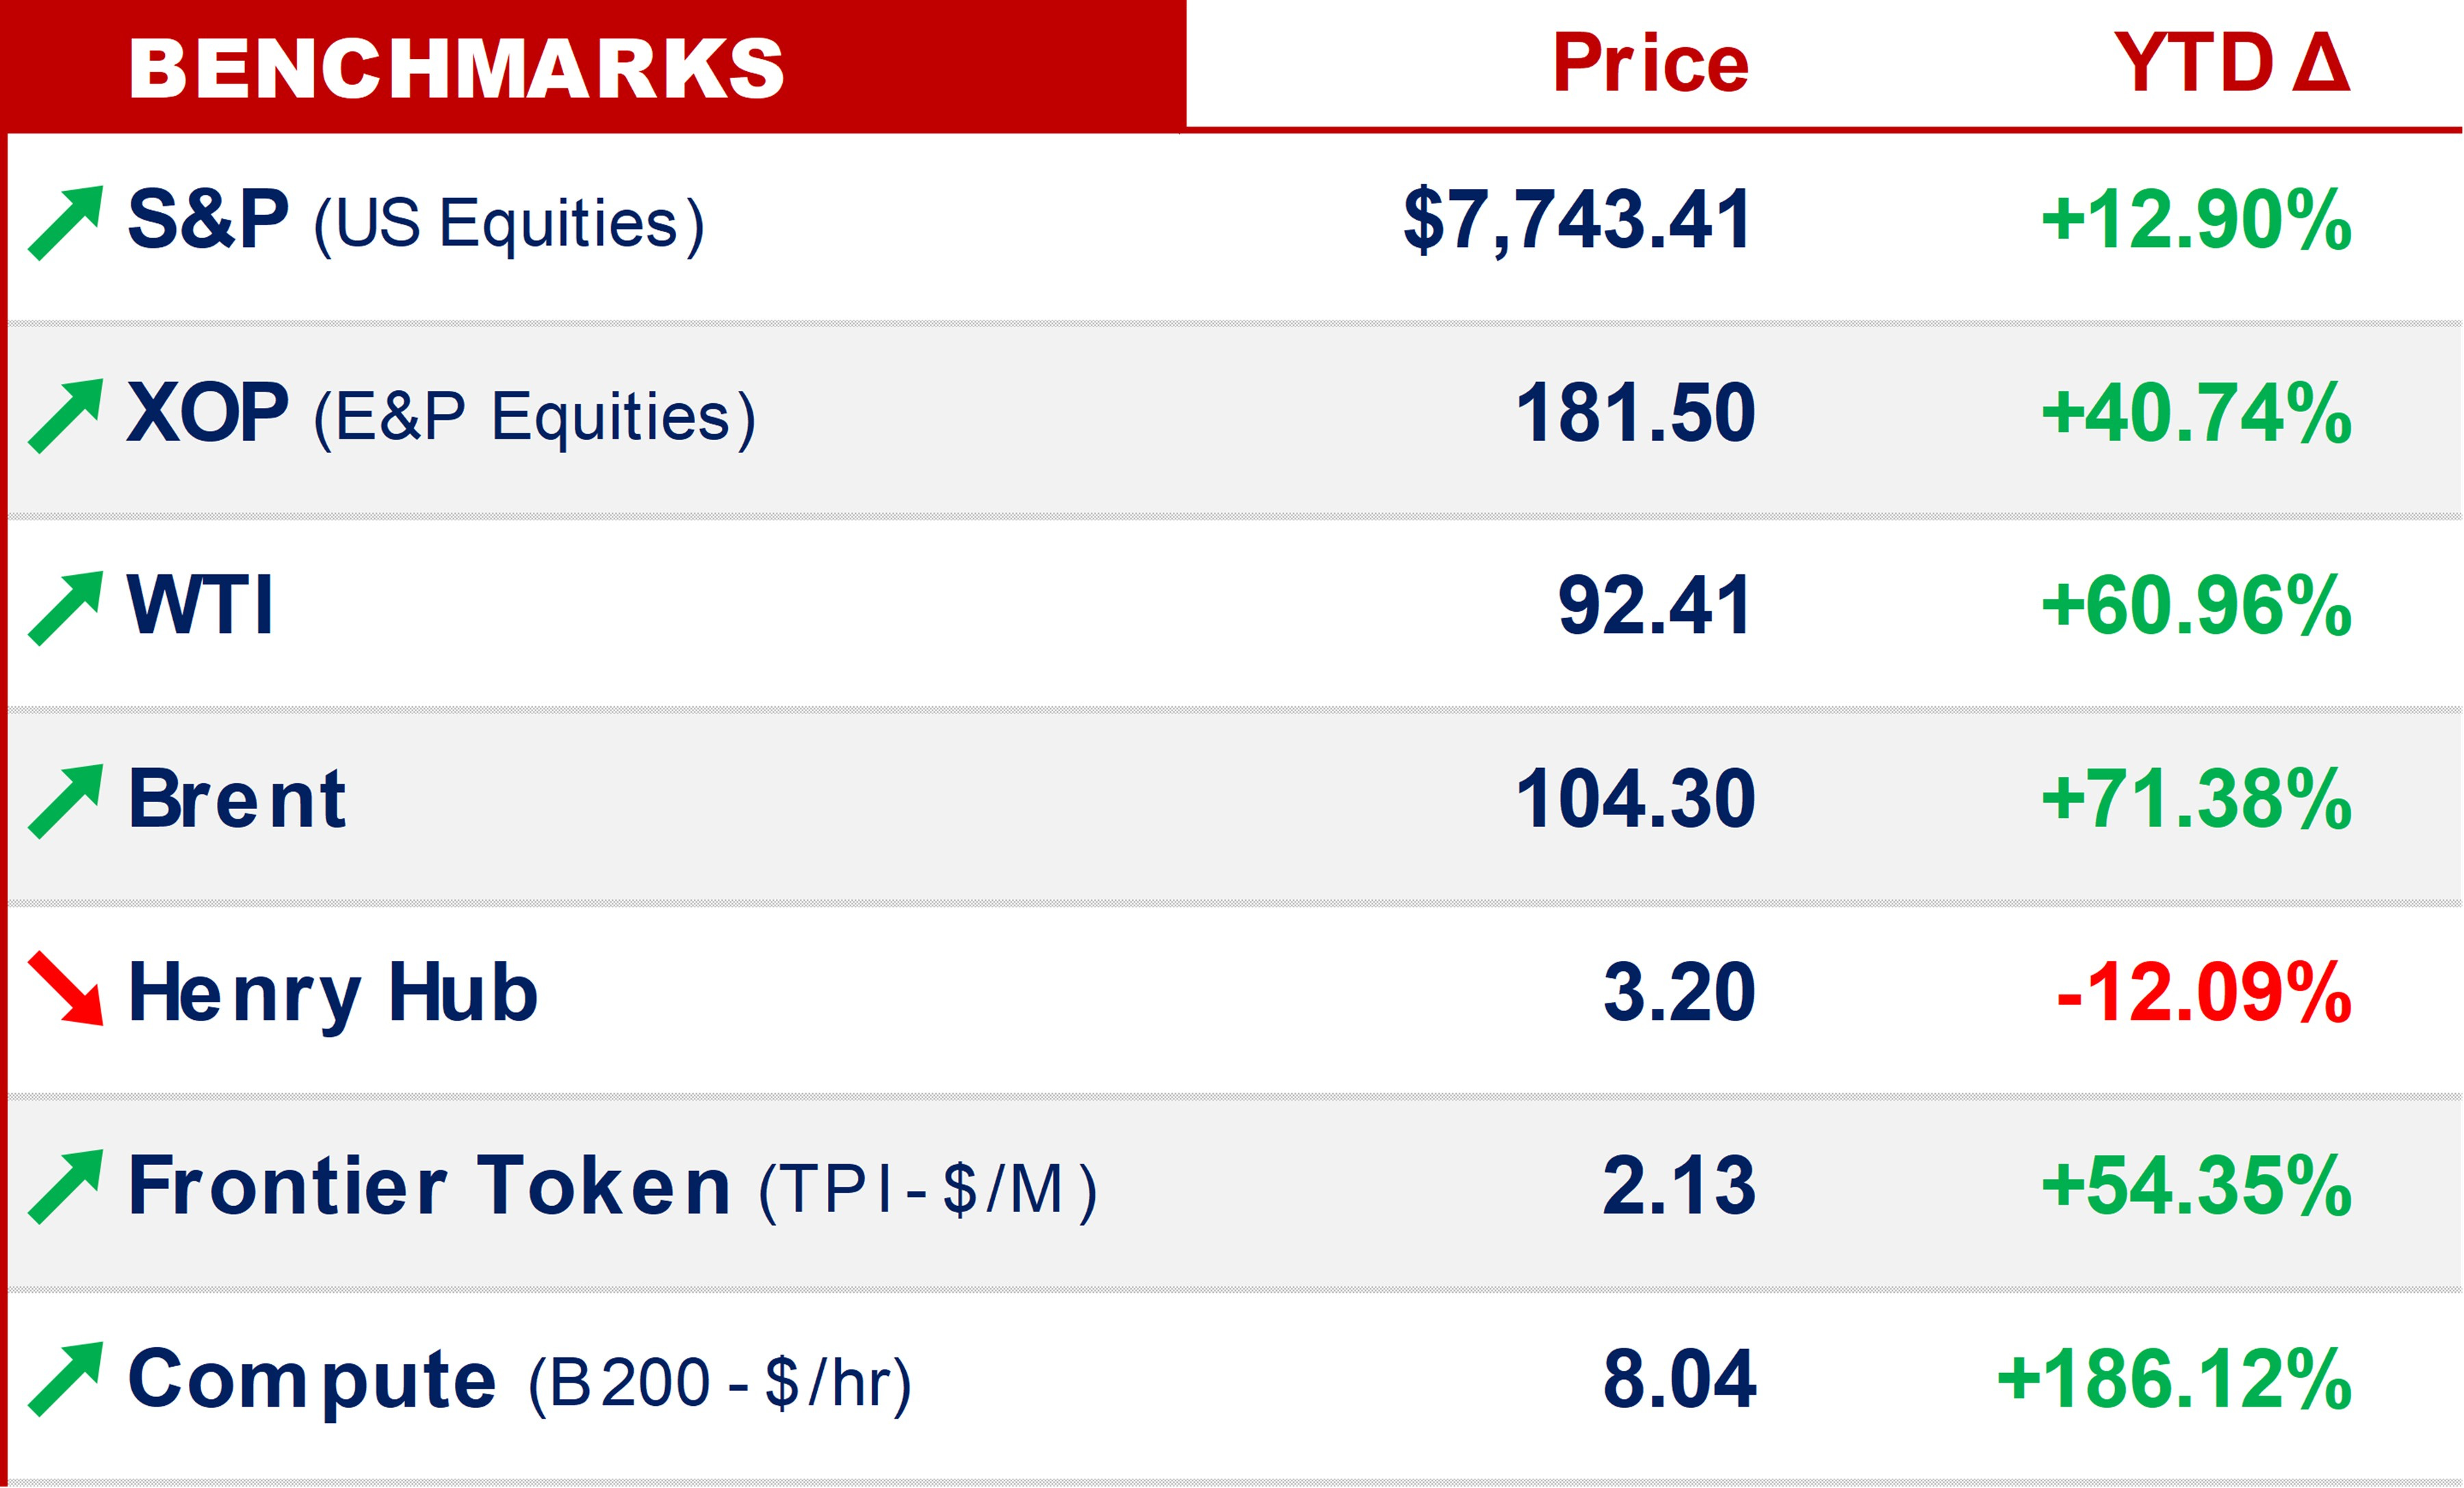
SPREADS.
Price chased headlines this week.
Oil slipped under $100 on Tuesday on the East-West restart & Hormuz reopening hopes. Brent then jumped 3.9% Wednesday after Pezeshkian’s “never surrender” at the UN, settled at $106.60 Thursday & gave back 2% Friday to $104.32 on signs of progress w/ Iran.
The spreads were more honest:
WTI traded as much as $12 under Brent on Thursday - the widest since early May (with current levels near that).
Gulf Coast diesel was ~$210/bbl on 22 Sep (EIA spot) - more than $110 over WTI.
A crack that wide isn’t a crude shortage. It’s a shortage of refining & delivery.
North Sea grades are still standing in for missing Gulf sours. Sverdrup offers hit Dated+$35 last week (Bloomberg), vs a record Platts assessment of +$19.55. There’s been little fresh pricing since - watch whether premiums ease as Yanbu comes back.
Then, Wednesday’s scare: a Politico report that a 90-day US fuel-export ban was being prepared knocked ULSD down ~5% intraday.
The White House denied it, & ULSD settled 3.4% lower at ~$4.78/gal.
It’s also what WTI’s discount is pricing - diesel trapped at home means US refiners need less crude.
At the pump & in the tanks:
AAA diesel set a record $6.53 this week.
EIA distillates drew to ~107.4mb (w/e 18 Sep) while crude stocks unexpectedly built 3mb.
Crude building, distillate drawing - the week in one print.
And it’s leaking into everything else:
Diesel & jet costs are now being passed through into cargo pricing.
The Fed hiked to 3.75-4% this month & has pencilled in another before year-end. Cleveland’s Hammack warned “an inflationary mindset could start to set in.”
So why was a ban plausible enough to trade?
5wks to the mid-terms…
…w/ retail diesel at a record.
The Catch-22 from two weeks ago (strike & own the war, or sit tight & own the inflation) has a third door: keep US fuel at home & export the shortage.
It’s closed for now…
…but the market now knows the door is there -
YANBU.
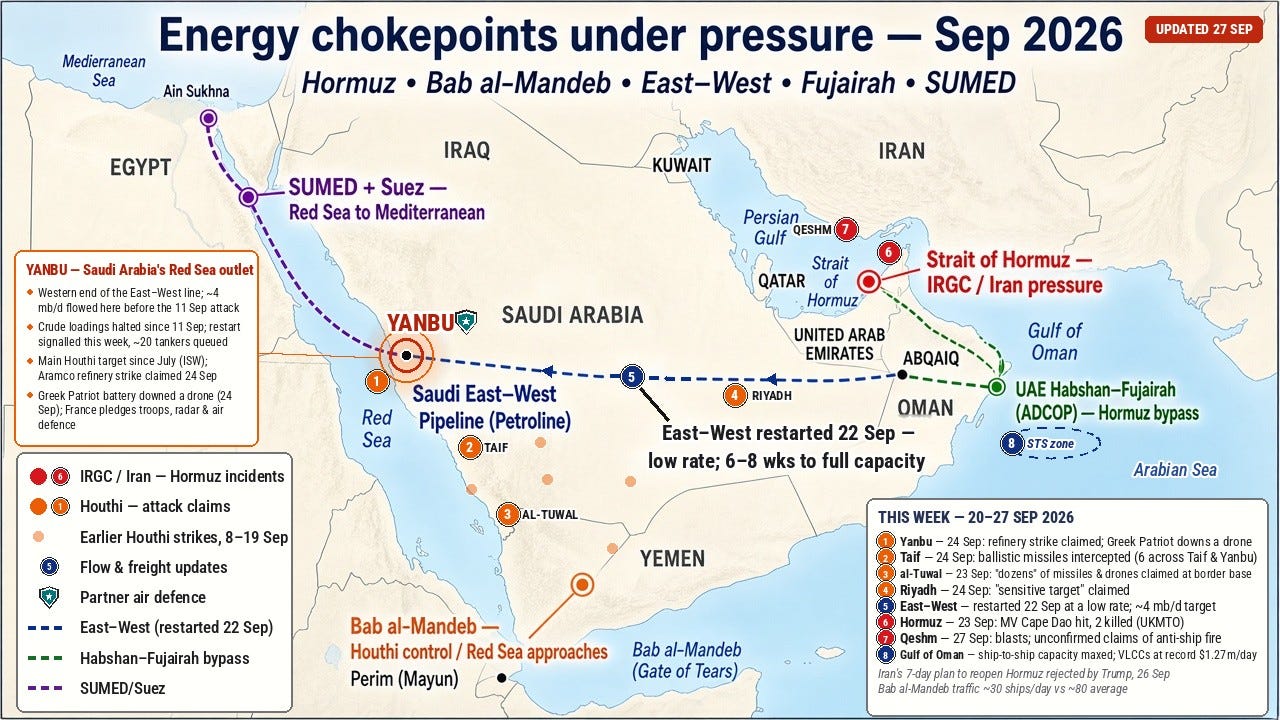
On Thursday night the Houthis claimed ballistic & cruise missiles & drones at Aramco’s Yanbu refinery & a “sensitive target” in Riyadh.
Riyadh says it intercepted six ballistic missiles.
Per ISW (25 Sep), Yanbu has been the main target since July - to “maximize Saudi political and economic costs.”
The terms for stopping…
End Saudi military activity & support for anti-Houthi forces.
Lift controls on Houthi-held ports & airports.
Pay war reparations & civil-servant salaries.
Hand the Houthis control of Yemen’s oil & gas.
Two weeks ago Riyadh was asking Washington for strikes. This week help came from other capitals - & it’s defensive:
Macron pledged “soldiers, radar systems and defense systems” to protect Yanbu.
London committed one RAF Voyager for “defensive air-to-air refuelling” - time-limited & under review.
Saudi, Pakistani & Turkish foreign ministers met Thursday to call an urgent meeting of their military chiefs under the Mecca defence pact.
ISW’s read: the Houthis are now in a bind. Hit partner forces & invite a much bigger response - or leave them be & watch the campaign lose its edge.
Meanwhile, the barrels:
The East-West line restarted Tuesday, “pumping at a low rate.” Aramco aims to get back to its pre-attack ~4mb/d (capacity 7mb/d), w/ full recovery 6-8wks out (Reuters).
JPM had Saudi crude through Hormuz at ~2.9mb/d in the six days to 18 Sep.
VLCC rates hit a record $1.27m/day on Monday (Reuters), w/ transfer capacity off Oman reportedly maxed out.
Saudi’s Red Sea route is under fire, its Hormuz route runs at record freight…
… & the air cover is arriving just as Yanbu & the East-West line decide how many Saudi barrels reach the market -
REFINERIES.
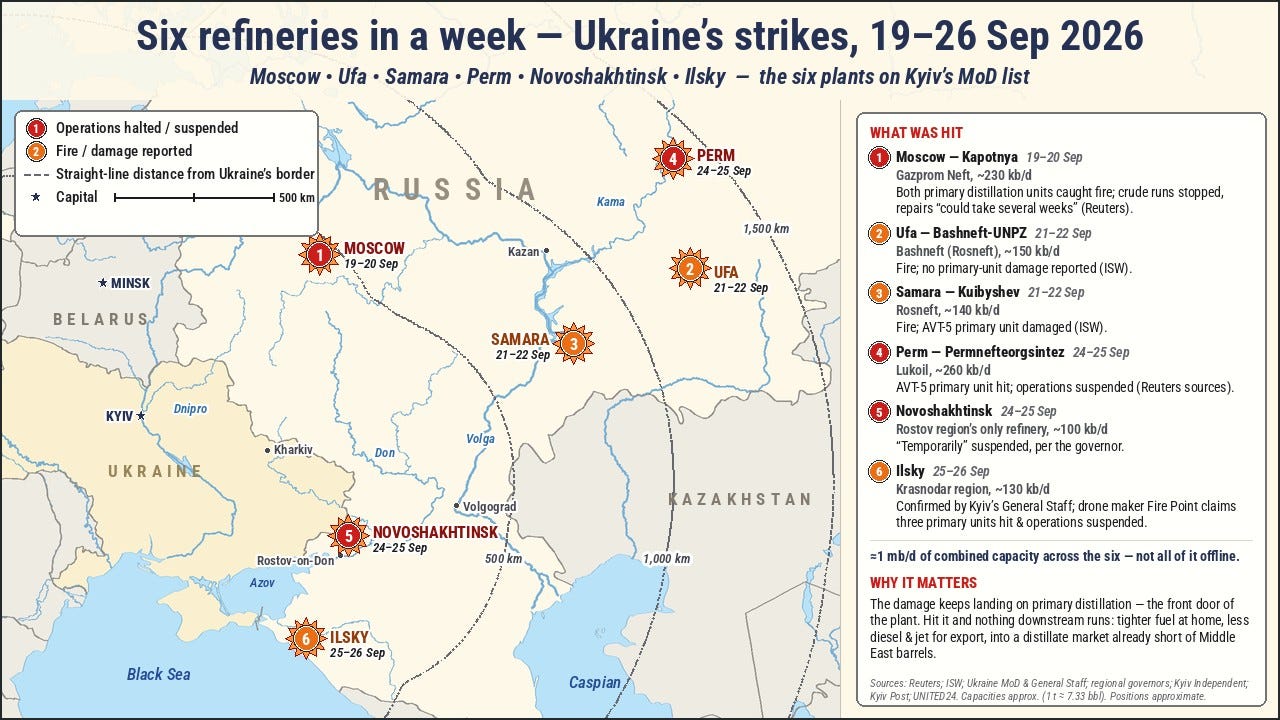
Kyiv’s MoD counts six refineries hit in a week, at ranges of up to 1,600km:
Moscow (Kapotnya), 19-20 Sep - Reuters: crude runs stopped after both primary distillation units caught fire; repairs “could take several weeks.” ~230kb/d.
Ufa (Bashneft) & Samara (Kuibyshev), 21-22 Sep - fires at both, primary-unit damage at Kuibyshev.
Perm (Lukoil), 24-25 Sep - primary unit hit, operations suspended per Reuters sources.
Novoshakhtinsk, 24-25 Sep - Rostov’s only refinery, “temporarily” suspended per the governor.
Ilsky, 25-26 Sep - confirmed by Kyiv’s General Staff.
Note where the damage keeps landing: primary distillation - the front door of the plant. Hit it & nothing downstream runs.
That’s a products problem:
Less refining tightens Russia’s own fuel market & cuts the diesel & jet it can export - into a distillate market that’s already lost much of its Middle East supply.
It also tends to push more Russian crude toward export - & Washington now has a tool aimed at the buyers. The Russia-Iran sanctions act Trump signed on 18 Sep allows tariffs of up to 100% on the five largest buyers of Russian oil & gas.
None imposed yet.
India says it’s “studying” the law… the question is whether India & Arab buyers cut anyway -
HORMUZ.
Friday’s close priced progress. The weekend didn’t deliver it.
Iran’s seven-day plan went public Friday: ~$12bn of frozen assets released, oil sanctions lifted, the US naval blockade ended & fighting stopped, incl. in Lebanon - then Hormuz reopens.
Trump reportedly rejected it Saturday.
Overnight into Sunday, explosions near Qeshm, w/ unconfirmed claims that anti-ship missiles & drones were fired at commercial vessels. Tehran hasn’t confirmed any attack.
The squeeze on Tehran keeps widening:
Per the WSJ, Treasury has pressed 50+ countries to cut Iran’s banking & aviation links. Oman, the UAE, Turkey, Azerbaijan & Georgia have cut ties w/ Iranian airlines or banks.
Javi Blas flagged the Hormuz wording out of the Trump-Xi summit. The White House fact sheet: no country can be allowed to “impose tolls on international waterways.” Hormuz isn’t named - it doesn’t need to be.
Weeks of absorbing shocks have used up the market’s buffers.
The next one lands on a market w/ no slack…
… & Monday opens on a rejected plan & explosions off Qeshm -
OTHER.
Argentina LNG Update: US EXIM / Trump backing Milei’s LNG
Exxon & Socar: Shale JV in Azerbaijan
That’s it for this week -