
“Insurance always looks expensive the day after nothing happens” - this newsletter
Editor’s note: last week, the credit market was paying up for war insurance. This week, the oil market priced in a peace deal - before anyone had signed one.
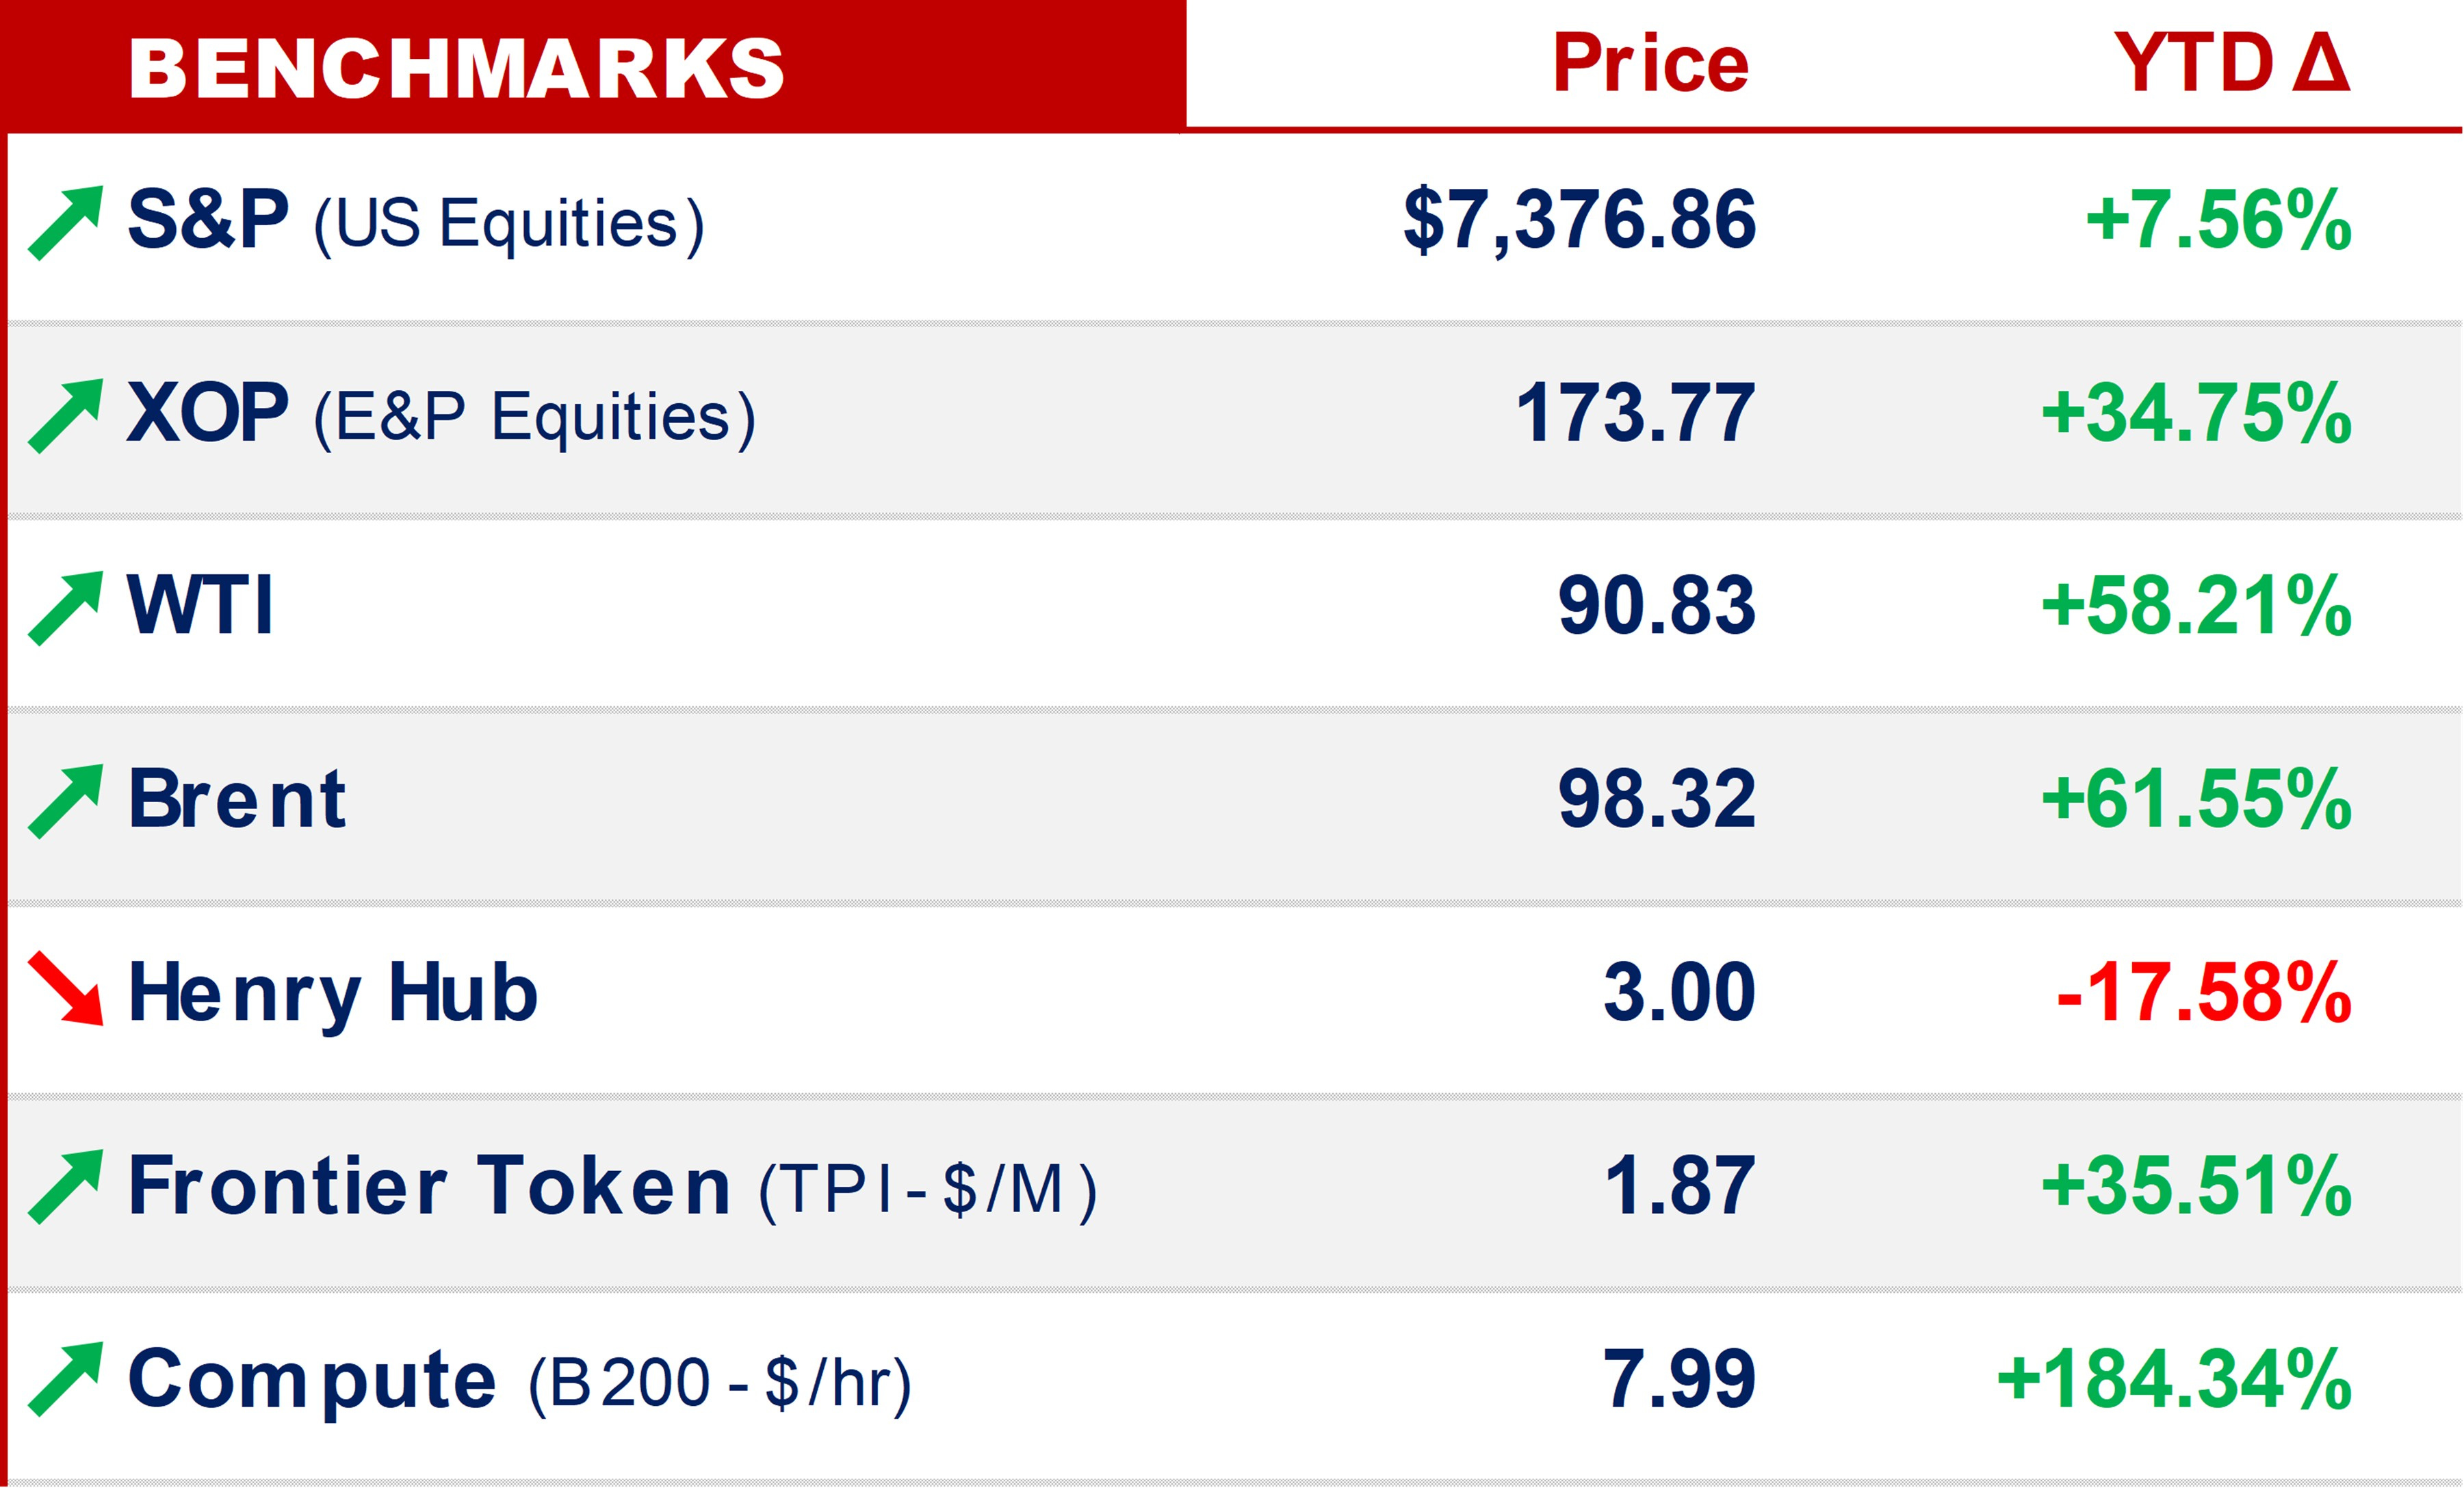
PRICED IN.
They say buy the rumor, sell the news. Well, crude sold the rumor -
WTI fell ~13% too, to $90.83
Measured from the expiring Dec contract ($117.64), it’s ~16% - which some are calling the steepest weekly fall since 2020
The worst of it came Wednesday, the day after the midterms: Brent fell 9.2% in a session, to $94.11
What’s priced: a US-Iran deal.
What’s signed: nothing.
Markets have done this before.
On Jan 17th, 1991 - the morning after Desert Storm’s air war began - crude fell $10.56 to $21.44, a record 33% in one session.
Traders priced the end of a war, before it ended.
This week, they priced a peace that doesn’t exist, yet.
Hedge funds didn’t wait either: a net 78MM barrels of crude futures sold in the week to Nov 3rd, the most since mid-June.
That’s a crowded trade. And if the talks stall, the way back will be just as crowded.
Last week, credit was paying ~16bps to hold energy bonds as war insurance.
This week, the market cancelled the policy.
And… nobody told the Gulf -
THE GULF.
Nov 2nd: the US carried out what officials called limited, defensive strikes on Iran’s Qeshm Island, after Iranian surface-to-air fire at US assets (CNN). ISW says the US hit Iranian air defenses on Qeshm again on Nov 6th
Saturday night: early, unverified OSINT reports of a US-Iran exchange of fire around Bandar Abbas & Qeshm, & a fire at the port of Jask
Saudi: on Sunday, a Houthi missile attack damaged Aramco’s tower in Riyadh’s financial district - windows blown out across several floors.
Tehran: ISW says Iran’s leadership reads the midterm result as proof its strategy is working, & Mojtaba Khamenei is sticking with maximal demands
The detail that matters: the Grit was on the blacklist of Iran’s self-styled Persian Gulf Strait Authority. These aren’t random hits - they’re enforcement.
A strait that’s being policed by one side isn’t a strait that’s about to reopen on the other side’s terms.
And none of the weekend was in Friday’s settle -
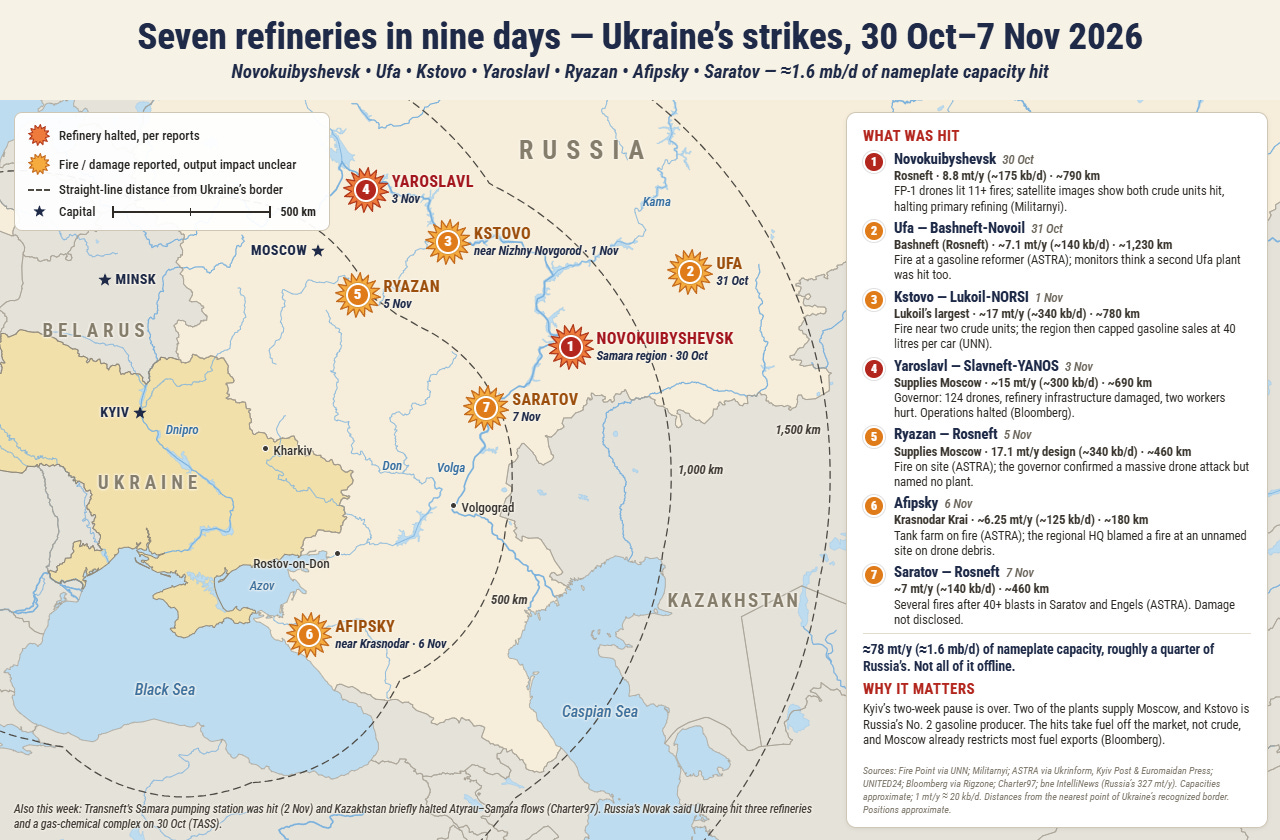
SEVEN REFINERIES.
Nine days, seven refineries - & what they take off the market is product, not crude -
By Tom Kloza’s count, Ukraine has hit 7 Russian refineries since Oct 30th:
Oct 30th - Novokuibyshevsk (Rosneft, Samara region)
Oct 31st - Ufa - a fire in the industrial zone that houses Bashneft’s plants (Charter97)
Nov 1st - Kstovo (Lukoil’s NORSI - Russia’s 4th-largest refinery & its 2nd-largest gasoline producer). The Nizhny Novgorod region then capped gasoline at 40 litres per car & banned canister sales - but set no limit on diesel (UNN)
Nov 3rd - Yaroslavl (Slavneft-YANOS, one of Russia’s 5 largest). The governor claimed 124 drones & conceded refinery infrastructure was damaged (UNITED24)
Nov 5th - Ryazan (Rosneft, ~5% of Russia’s refining capacity). Fire on site; the governor confirmed a massive drone attack but didn’t name the plant (Kurs)
Nov 6th - Afipsky (Krasnodar)
Nov 7th - Saratov (Rosneft)
Add it up & it’s well over 1MM b/d of nameplate capacity, on our math - hit, not necessarily offline.
Now look at what comes off the market.
Not crude - product.
A Russian refinery that can’t run turns its crude into an export barrel:
Bearish crude - more Russian barrels looking for a home
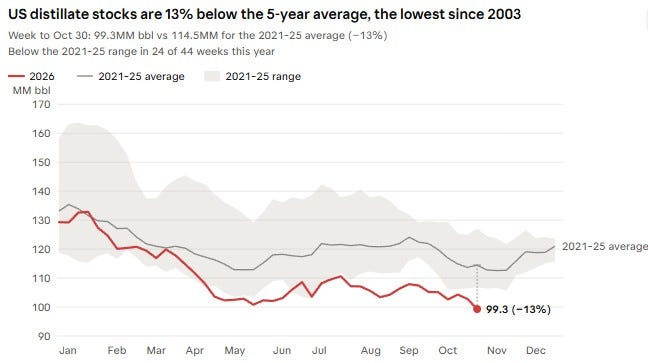
Bullish diesel - fewer Russian molecules in the product market
Same split the futures market showed this week.
The exception: on Nov 2nd, a strike on Transneft’s Samara pumping station led Kazakhstan to temporarily halt flows on the Atyrau-Samara pipeline (Charter97). That one was crude.
Meanwhile, Moscow sent 172 drones & 36 ballistic missiles at Ukraine’s grid on Nov 6th-7th.
Both sides are aiming at the other’s winter -
OTHER NEWS.
Trafigura, Vitol, Mercuria & ADNOC are seeking US approval to use sanctioned tankers. Companies have to apply to Treasury to use the vessels (Baird Maritime, citing Reuters)
Red Sea: Bab al-Mandeb & Suez transits are back above half of pre-closure levels, & Maersk is above two-thirds. The Houthis are issuing “transit permits”; the email address for the permits is apparently clearances@hocc.gov.ye… (in addition to missiles, spam is now certainly inbound - h/t Malin)
That’s it for this week - enjoy the week ahead -