
“The battle is fought & decided by the quartermasters before the shooting begins” - Rommel
CRACKS.
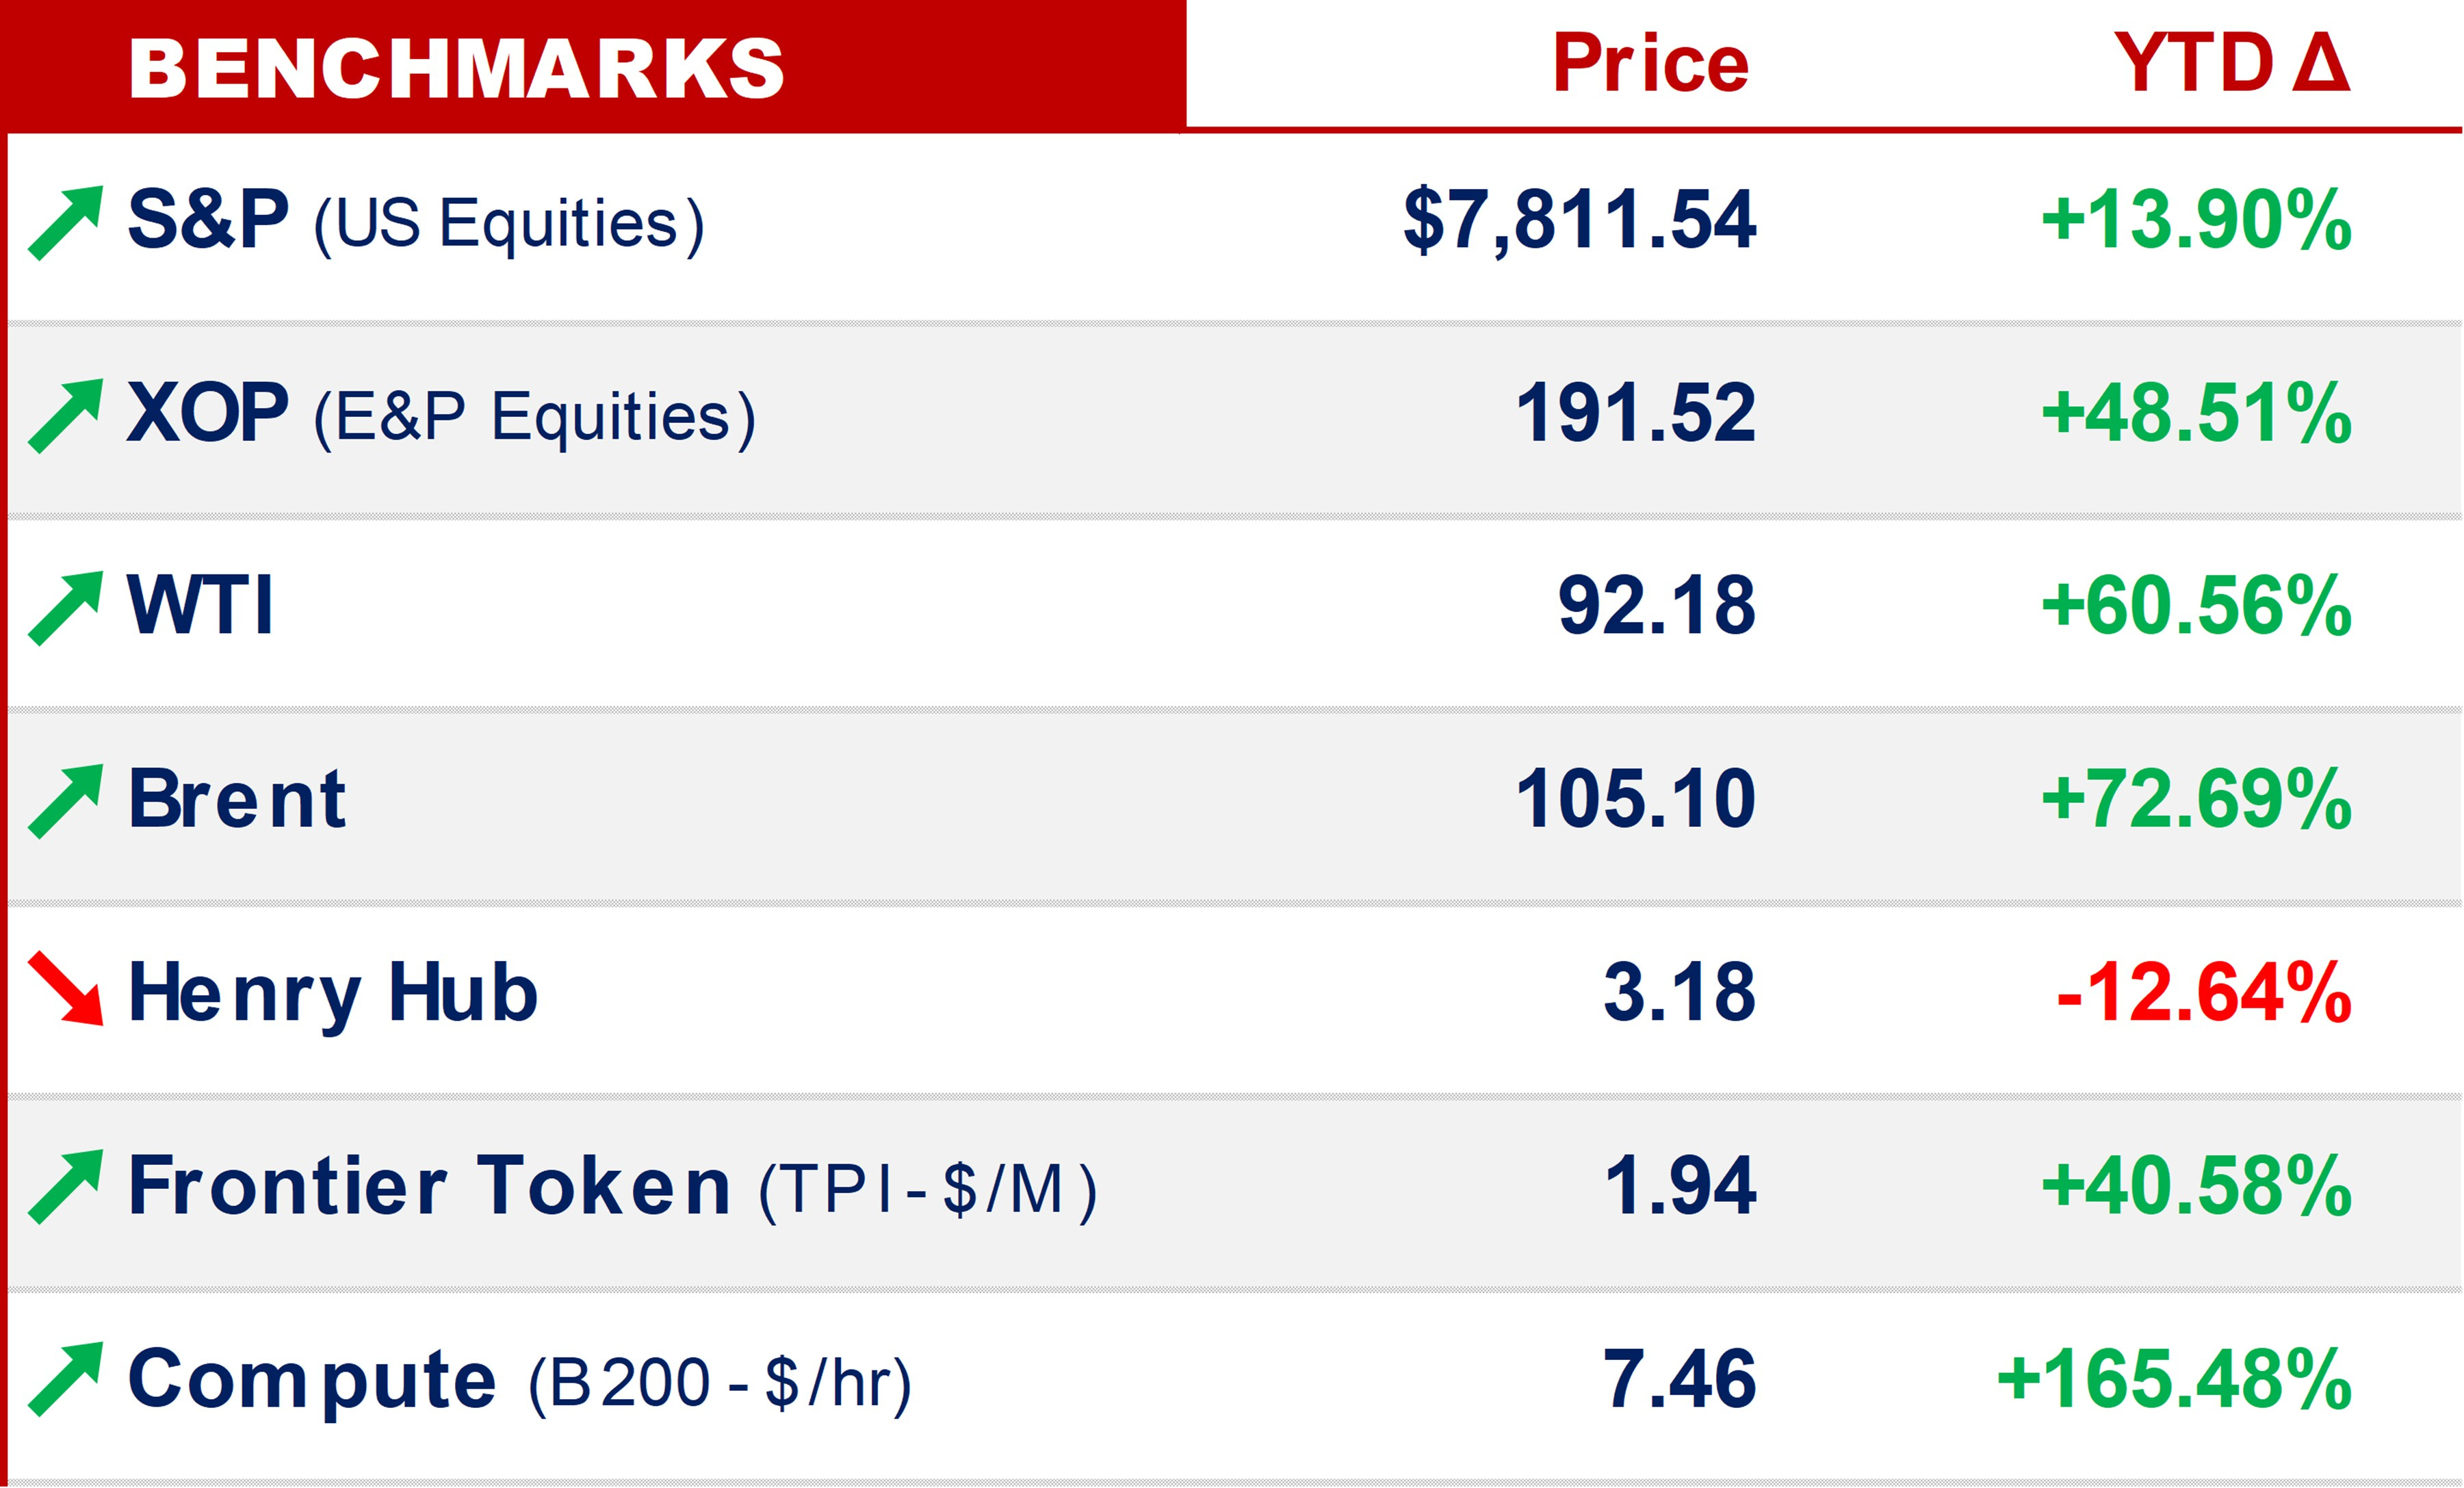
Dated Brent settled at ~$136 on Oct 8th…
…with Brent futures near $104…
…and spot diesel clearing $200 a barrel at several US hubs
A Dated Brent-to-futures gap of >$30/bbl was the world this week.
With EU onshore crude inventories near 5yr averages, the solution would normally be drawing inventories.
The right question, as Anton Likhodedov asked, is “this disbalance appropriate for the current distress level or it is the result of traders' games?”
We suspect a level gaming…
Moving on - Middle East crude exports had got almost back to pre-war levels by routing around Hormuz; Iran's stepped-up campaign against shipping is now reversing part of the recovery in Hormuz flows, and refined product exports from the region are still 2.5MM b/d below where they were.
And the conflicts continue to get wider on three fronts at once: Saudi Arabia, Hormuz, & Russia's refineries.
As Russian refineries continue to be hit / taken off-line, the economic effect - with Russian crude being exported - is that the crack spreads are being moved out of Russia -
RUSSIA.
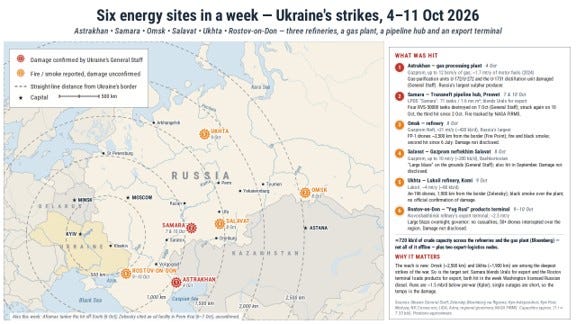
Ukraine's campaign reached further than ever.
Drones hit the Omsk refinery, one of Russia's largest and about 2,800 km from the border, plus Salavat in Bashkortostan on Oct 8th & Lukoil's Ukhta refinery on Oct 9th, the fourth refinery hit that week, and on Oct 10th the Yug Rusi products terminal in Rostov-on-Don was hit, with large explosions.
The cumulative effect is the point.
Kpler has Russian refinery runs at 4MM b/d against 5.6MM pre-war, with crude exports at a five-year high of 4.3MM b/d because crude that can't be refined gets shipped instead.
Most individual strikes cost under a month of downtime.
It is the repetition - a refinery hit every three days by the IEA's count - that keeps the number there.
The corollary cuts both ways: if the strikes stopped, Kpler thinks Russian flows could be near normal by year-end.
US policy, meanwhile, is pulling the other way.
Trump & Putin agreed Russian diesel exports, the US Treasury issued a licence lifting sanctions until April 2027, and Russia partly eased its own export ban to allow 500k tonnes, or 125k b/d for a month.
Russia was exporting more than 1MM b/d of diesel at the end of 2025.
The licence is not the diesel policy.
The diesel policy is Trump telling Ukraine yesterday "don't hit refineries" -
OTHER.
The US 30yr yield hit its highest since ‘02, and Pimco thinks the 10yr could reach 6%
Hurricane Isaias shut in about 70% of Gulf of Mexico oil & 59% of gas
Houthis strike Riyadh airport, again
That’s it for today - enjoy the week ahead -